Updated October 2026 with the 2026 IRMAA brackets and Part B premium.
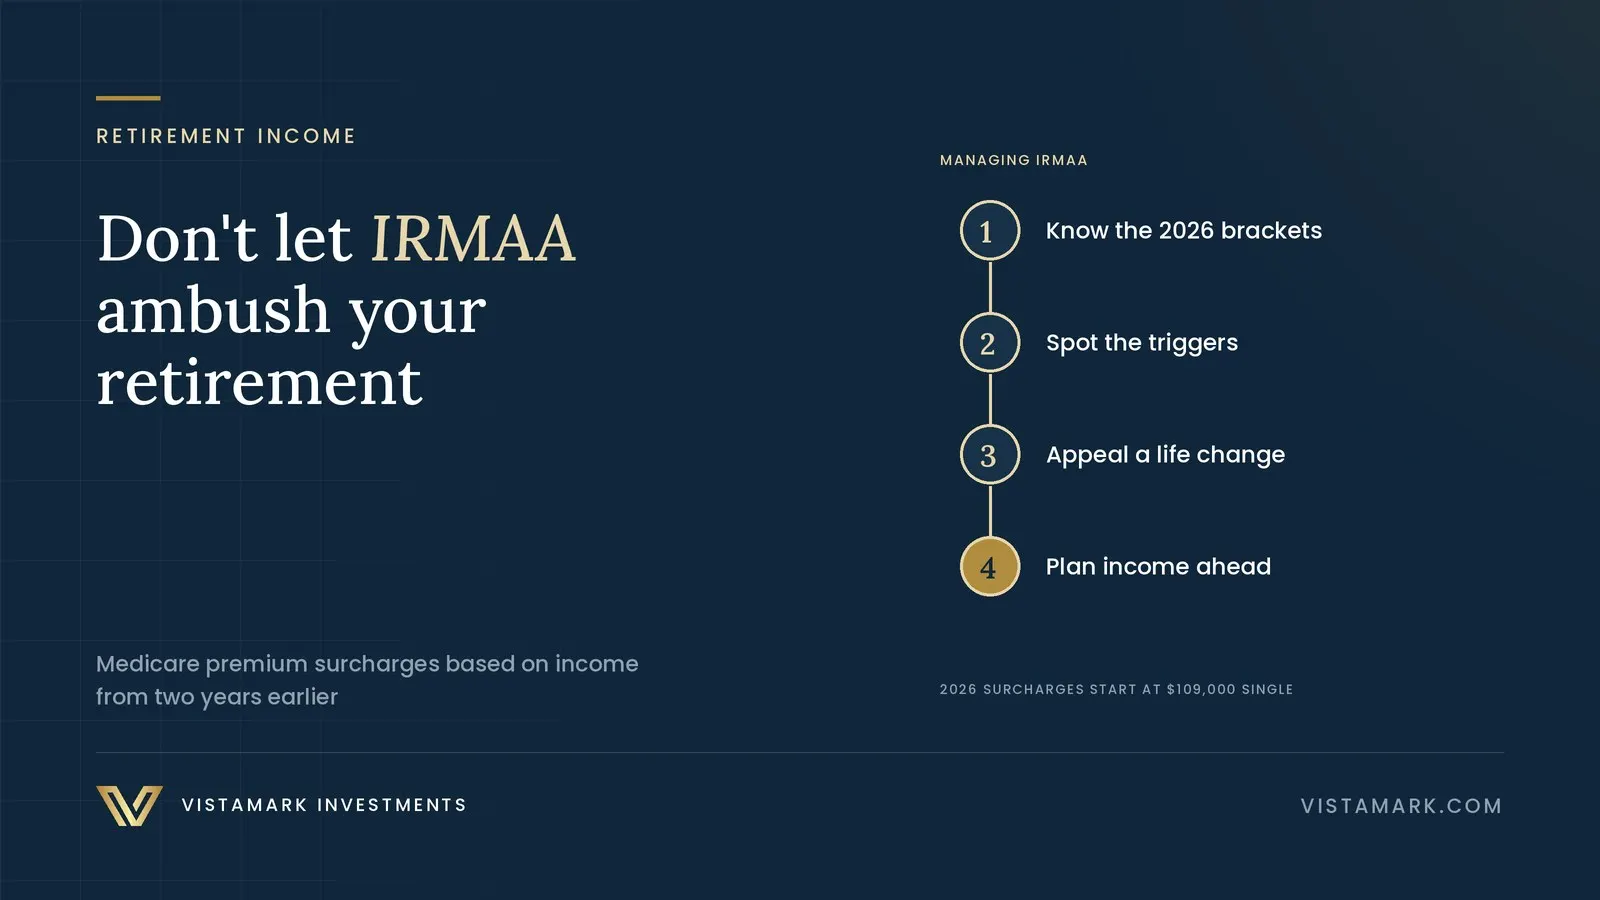
Retirees plan carefully for taxes, but many are surprised by a second, quieter charge: the Medicare Income-Related Monthly Adjustment Amount, or IRMAA. It raises Medicare premiums for people with higher incomes, and because it is based on income from two years earlier, a single large year, often the year you retire or sell something, can raise premiums after your income has already fallen.
What is IRMAA?
IRMAA is a surcharge added to Medicare Part B (medical insurance) and Part D (prescription drug) premiums when your modified adjusted gross income (MAGI) exceeds set thresholds. MAGI for this purpose is your adjusted gross income plus tax-exempt interest. The Social Security Administration uses your tax return from two years earlier, so 2026 premiums are based on 2024 income, and 2028 premiums will be based on 2026 income.
What are the 2026 IRMAA brackets?
The standard Part B premium in 2026 is $202.90 a month. The surcharges begin at $109,000 of 2024 MAGI for single filers and $218,000 for married couples filing jointly:
| 2024 MAGI, single | 2024 MAGI, joint | 2026 Part B premium per person, per month |
|---|---|---|
| $109,000 or less | $218,000 or less | $202.90 |
| Over $109,000 to $137,000 | Over $218,000 to $274,000 | $284.10 |
| Over $137,000 to $171,000 | Over $274,000 to $342,000 | $405.80 |
| Over $171,000 to $205,000 | Over $342,000 to $410,000 | $527.50 |
| Over $205,000 to $500,000 | Over $410,000 to $750,000 | $649.20 |
| Over $500,000 | Over $750,000 | $689.90 |
Part D adds a separate surcharge in the same brackets, from $14.50 to $91.00 a month per person in 2026. For a married couple in the top bracket, the combined Part B and Part D surcharges come to more than $13,000 a year. The brackets are cliffs: one dollar over a threshold triggers the full surcharge for that tier.
What commonly triggers IRMAA?
- The last working year, including bonuses, deferred compensation and severance.
- Stock compensation vesting or being exercised around retirement.
- Capital gains from selling a business, a home above the exclusion, real estate or concentrated stock.
- Roth conversions, which add the converted amount to income.
- Required minimum distributions, which begin at age 73 for most current retirees and rise every year.
Can you appeal IRMAA?
Yes, if your income has dropped because of a qualifying life-changing event. You request a new determination from the Social Security Administration using Form SSA-44, with documentation and an estimate of your current-year income. Qualifying events are:
- Work stoppage or reduction in work hours, which covers retirement.
- Marriage, divorce or annulment, or the death of a spouse.
- Loss of income-producing property due to a disaster or other event beyond your control.
- Loss or reduction of certain pension income.
- An employer settlement payment due to the employer's closure, bankruptcy or reorganization.
A one-time capital gain or a Roth conversion is not a life-changing event. For those, planning is the only remedy.
How can you plan to reduce IRMAA?
- Project MAGI two years ahead. Each year's income decisions set your premiums two years later, so build IRMAA brackets into tax projections from about age 63 onward.
- Manage the cliffs. If a Roth conversion or gain would push income just over a threshold, consider converting or selling less, or splitting the transaction across tax years.
- Use qualified charitable distributions. After age 70½, gifts made directly from an IRA to charity are excluded from income and count toward required distributions from age 73.
- Consider asset location and tax-efficient investing, holding income-producing assets in tax-deferred accounts and harvesting losses in taxable accounts.
- Weigh the trade-off. Paying a temporary surcharge in exchange for a Roth conversion can still be worthwhile if it lowers lifetime taxes and future required distributions; IRMAA is a cost to manage, not something to avoid at any price.
Does the One Big Beautiful Bill Act affect IRMAA?
Not directly; the brackets are set under Medicare law and adjusted for inflation each year. But the law's other changes, including the new state and local tax deduction phase-down above roughly $500,000 of income and the charitable deduction floor, make coordinated income planning more valuable, because several thresholds now sit near the same income levels. Our 2026 year-end planning guide covers the broader picture.
Where should you start?
Check your most recent Medicare premium notice to see which bracket you are in and which tax year it is based on. If income has dropped because you retired, file Form SSA-44. If large income events are ahead, model them against the brackets with your CPA before they happen. This article is general information, not tax advice; the VistaWealth Office builds IRMAA into retirement income planning for the families we serve.
This article is part of our Tax Planning Guide, which collects our writing on the topic with answers to common questions.
Founder and CIO of Vistamark; as CIO of Fiducient Advisors, oversaw investment strategy for more than $260 billion in client assets. More about Matthew →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.