For many of us, Social Security isn’t just a government program; it’s a cornerstone of our retirement dreams. But here’s the kicker: the timing and method you choose to claim those benefits can dramatically shape your financial landscape for decades to come. It’s not a one-size-fits-all decision, and getting it right is crucial for a secure and comfortable retirement.
While your Social Security claiming strategy is distinct from your Medicare enrollment choices (Original Medicare versus Medicare Advantage, for example), the thought process behind both is remarkably similar. In both cases, you’re weighing your personal circumstances, future needs, and financial goals to make a long-term decision. Let’s delve into the primary considerations that should guide your Social Security claiming strategy.
The Age-Old Question: When to Claim?
This is perhaps the most immediate factor impacting your Social Security benefits:
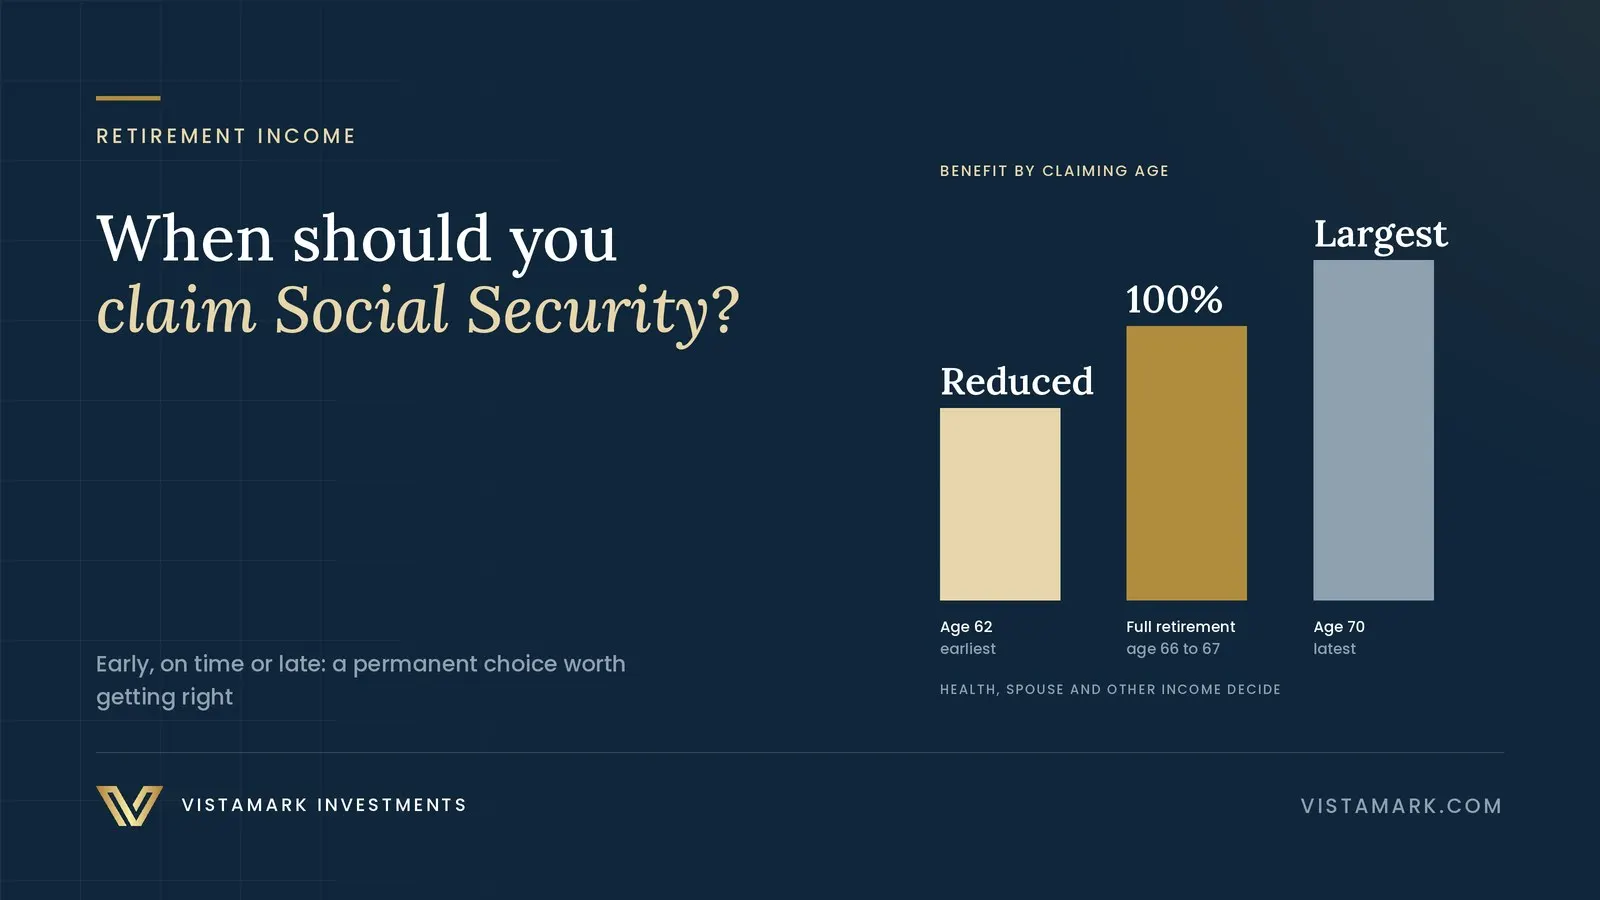
- Claiming Early (as young as 62): You get benefits sooner, but at a permanently reduced monthly amount. Think of it as trading immediate access for a smaller piece of the pie.
- Full Retirement Age (FRA - typically 66 or 67): This is your sweet spot for receiving 100% of the benefit you're entitled to based on your earnings history.
- Delaying Your Claim (up to age 70): This is where the magic of "delayed retirement credits" comes in. For every year you wait past your FRA, your monthly benefit increases significantly, offering the highest possible payment.
The Crystal Ball: Your Life Expectancy
This might sound a bit morbid, but your health and family history are vital clues:
- Expecting a Long Life? If longevity runs in your family and you're in good health, delaying your claim often leads to the highest total lifetime benefits. Those larger monthly checks really add up over the years.
- Health Concerns? If your health is compromised or you anticipate a shorter lifespan, claiming earlier might be the more pragmatic choice, ensuring you receive benefits when you need them most.
The Family Dynamic: Marital and Family Status
Your relationships can open up surprising claiming opportunities with Social Security:
- Married Couples: This is where coordination becomes key! Spouses can strategize together to maximize their household's total benefits, often by one spouse delaying their claim while the other claims earlier.
- Divorced or Widowed? Don't overlook potential spousal or survivor benefits. You might be eligible to claim on a former or deceased spouse's record, which can significantly impact your personal claiming timeline.
- Dependent Children: If you have minor or disabled dependent children, they may also be eligible for benefits based on your earnings record, adding another layer to your strategy.
Your Financial Ecosystem: Other Retirement Income
Social Security rarely exists in a vacuum. Consider your broader financial picture:
- Ample Other Income? If you have healthy pensions, IRAs, 401(k)s, annuities, or even plan to work part-time in retirement, you might have the luxury of delaying Social Security and letting those benefits grow.
- Need Income Sooner? If other income sources are limited, claiming Social Security earlier might be a necessity to cover your living expenses.
The Math Equation: Break-Even Analysis
This is where numbers come into play. A break-even analysis is a useful tool to estimate the age at which the total benefits you'd receive from delaying your claim would surpass the total benefits from claiming early. If you live beyond that break-even point, delaying typically puts more money in your pocket over your lifetime.
The Tax Tangle: Understanding the Implications
Yes, your Social Security benefits can be subject to federal income tax, depending on your overall income. Strategically coordinating your Social Security claim with withdrawals from other retirement accounts can help you manage your tax liability and maximize your net benefit.
Your Vision Board: Personal Goals and Lifestyle
Beyond the numbers, your ideal retirement lifestyle matters.
- Do you dream of extensive travel?
- Want to start a passion project or a small business?
- Is leaving a financial legacy important to you?
Your Social Security claiming strategy should be a supportive pillar for these broader personal and financial aspirations.
The Bottom Line: Your Unique Path
There’s no universal “best” Social Security claiming strategy. It's a deeply personal decision that requires careful consideration of your individual health, financial standing, family situation, and retirement dreams. While this guide provides a strong foundation, the complexities often warrant a deeper dive. Consulting with a qualified financial advisor can provide invaluable guidance, helping you navigate these factors and make the most informed decision for your secure and fulfilling retirement. Don't leave this crucial piece of your financial puzzle to chance!
For more information and personalized guidance, please feel free to reach out to Vistamark Investments. You can contact us at 312-895-3001, visit our website at vistamark.com, or send us an email to info@vistamark.com.
Founder and CIO of Vistamark; as CIO of Fiducient Advisors, oversaw investment strategy for more than $260 billion in client assets. More about Matthew →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.