Few conversations are harder to start, and few matter more. Adult children often learn the state of their parents' finances in a crisis: a fall, a diagnosis, a hospital stay. By then, decisions are rushed, documents are missing and the parent may no longer be able to say what they want. Talking early, while everyone is healthy and calm, protects the parent's wishes and the family's relationships.
When is the right time to start?
Before you need to. Natural openings include a parent's retirement, the death of a friend or relative, a move, an estate plan update or the holidays, when families are together. Frame it around their wishes and your desire to carry them out, not around their money or your inheritance.
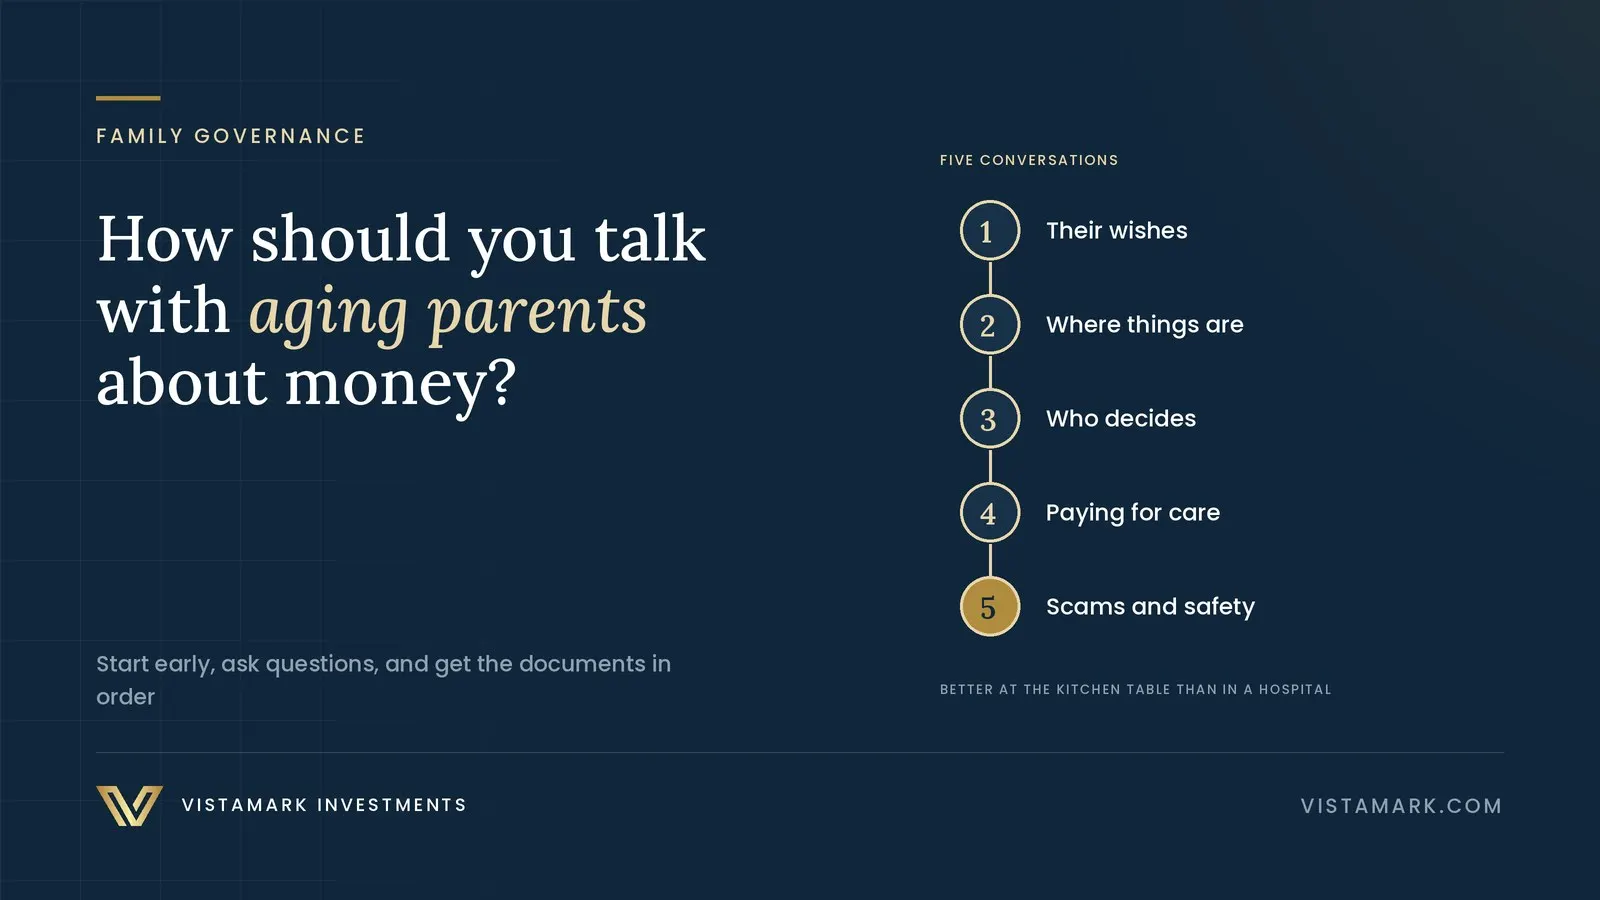
What are the five conversations to have?
- Their wishes. How they want to live as they age, where they want to live, what kind of care they would want and what matters most to them.
- Where things are. Accounts, insurance policies, estate documents, digital logins and the names of their advisors, ideally in a written inventory.
- Who decides. Who holds their financial power of attorney and health care power of attorney, and who is successor trustee, and whether those people know it.
- Paying for care. How long-term care would be funded: savings, long-term care insurance, home equity or family support.
- Scams and safety. How they will verify unexpected calls, emails and requests for money, and who they can call if something feels wrong.
Which documents should be in place?
- A current will and, often, a revocable trust.
- A durable financial power of attorney, recent enough that banks and custodians will honor it.
- A health care power of attorney and advance directive.
- Beneficiary designations that match the estate plan.
- Trusted contact forms at each financial institution, which let the firm reach someone if it suspects exploitation or confusion.
How can families recognize financial exploitation?
Warning signs include unusual withdrawals or wires, new "friends" or caregivers with influence over money, changes to wills or beneficiaries that seem out of character, unpaid bills despite adequate resources, and a parent who seems secretive or anxious about finances. Scams aimed at older adults, from fake government agents to romance scams and fake grandchildren in trouble, are common and sophisticated. Agree on a simple rule: no one sends money or shares account details in response to an unexpected request without first calling a family member or advisor.
How do you handle disagreements among siblings?
Include all siblings, even those who live far away, and share information openly to avoid suspicion. Divide responsibilities based on skills and proximity, and consider a neutral facilitator or the parents' advisor for the first conversation. If one sibling holds power of attorney, regular, transparent updates to the others prevent most conflicts. Our guide to family meetings about money offers a structure that works across generations.
What if a parent resists the conversation?
Respect their autonomy and keep the door open. Share why it matters to you, perhaps through a story about another family's experience, and ask for small steps: introducing you to their advisor, telling you where documents are kept or naming a trusted contact. Many parents are more comfortable talking with a neutral professional than with their children.
Where should you start?
Ask one question at the next family visit: "If something happened to you, is there anything you would want us to know or do?" Then listen. That conversation often opens the door to everything else. The VistaWealth Office works with families across generations, including meetings that bring parents and adult children together with their advisors.
This article is part of our Family Governance Guide, which collects our writing on the topic with answers to common questions.
Market Compass · weekly
Get the Compass by email
One concise recap of the week’s market-moving events and what to watch next, written by our CIO at the end of each market week.
Managing Partner, VistaWealth Office™ — integrated wealth planning for executives, business owners, family offices and charities. More about William →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.