Updated October 2026 for the One Big Beautiful Bill Act's AMT changes and the 2026 exemption amounts.
For several years after 2017, the alternative minimum tax (AMT) affected few households. That is changing. The One Big Beautiful Bill Act, signed in July 2025, kept the higher exemption amounts but made them disappear at lower incomes and twice as fast, starting in 2026. Combined with the higher state and local tax deduction, more high earners, especially executives with stock options and families in high-tax states, may find themselves paying it again.
What is the alternative minimum tax?
The AMT is a second way of calculating federal income tax. You start with regular taxable income, add back certain deductions and preference items, subtract an exemption and apply AMT rates of 26% and 28%. If that result is higher than your regular tax, you pay the difference as AMT. The most common add-backs are state and local taxes deducted on your return and the bargain element of incentive stock options (ISOs) exercised and held.
What changed for 2026?
| 2025 | 2026 | |
|---|---|---|
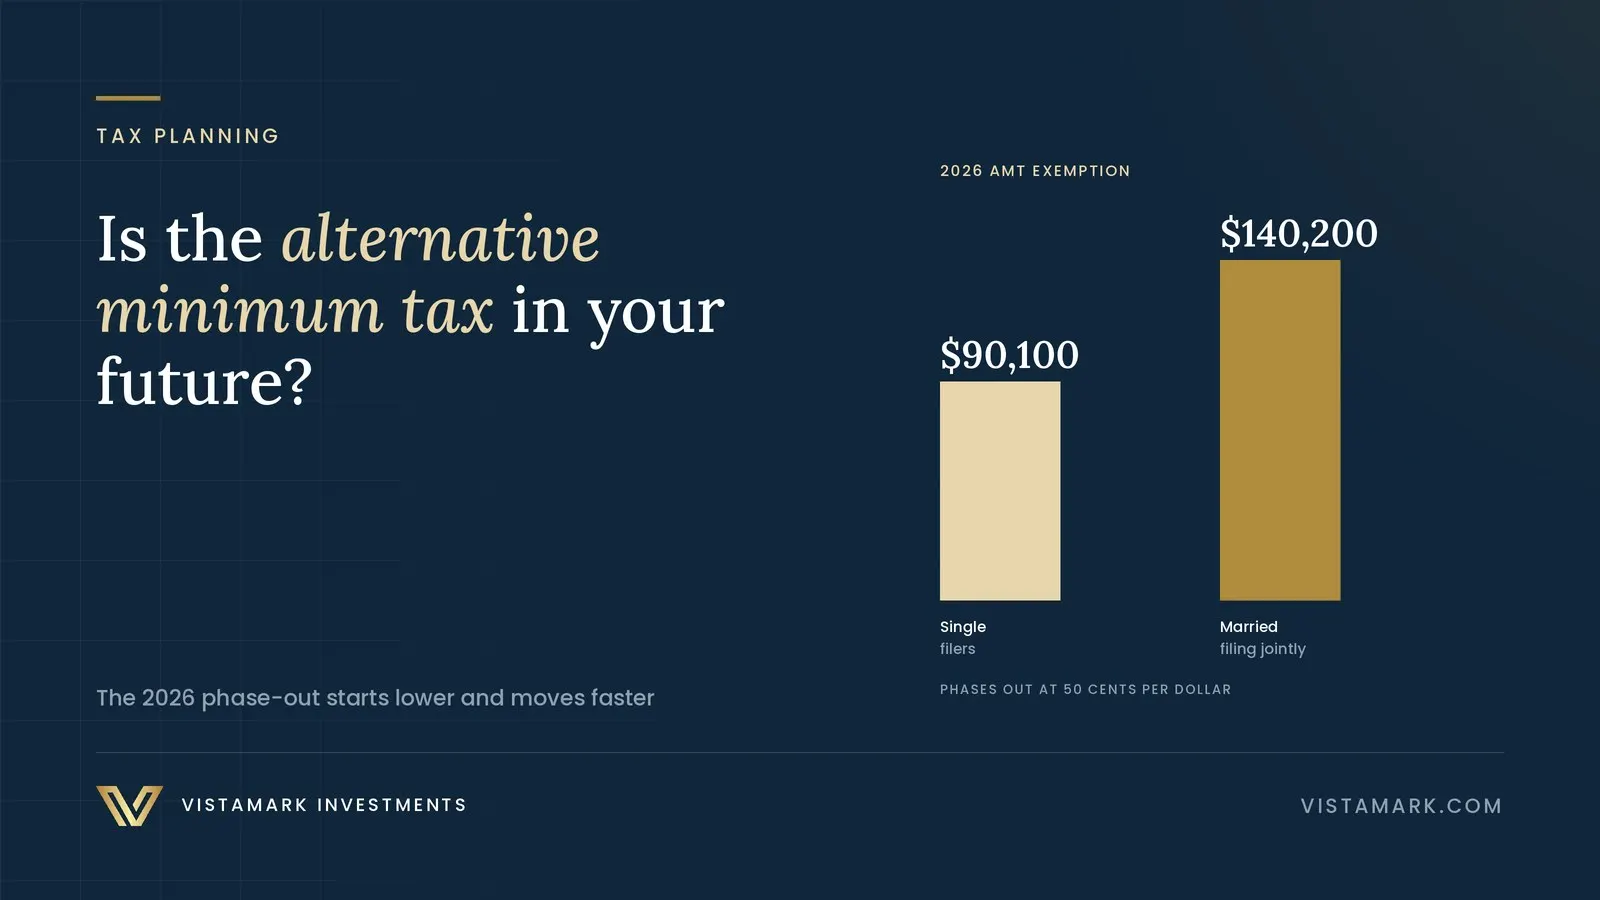
| Exemption, single | $88,100 | $90,100 |
| Exemption, married filing jointly | $137,000 | $140,200 |
| Phaseout starts, single | $626,350 | $500,000 |
| Phaseout starts, joint | $1,252,700 | $1,000,000 |
| Phaseout rate | 25 cents per dollar over the threshold | 50 cents per dollar over the threshold |
| 28% rate applies above | $239,100 of AMT income | $244,500 of AMT income |
The result is a zone where each extra dollar of income both adds AMT income and removes 50 cents of exemption. For a single filer, the exemption is gone entirely at about $680,200 of AMT income; for joint filers, at about $1,280,400.
Who is most likely to owe AMT now?
- Executives and employees exercising incentive stock options, because the spread at exercise counts as AMT income even if the shares are not sold.
- High earners in high-tax states who now deduct up to roughly $40,000 of state and local taxes for regular tax, all of which is added back for AMT.
- Households with income in the $500,000 to $1.3 million range, where the faster phaseout bites hardest.
- Taxpayers with large private activity bond interest, which is taxable for AMT.
How should incentive stock options be handled?
ISOs are the most common route into the AMT. Exercising and holding creates AMT income equal to the difference between the market price and the exercise price. Strategies include:
- Exercising in stages over several years, each sized to stay below the point where AMT begins.
- Exercising early in the year, which leaves time to sell in the same year as a disqualifying disposition if the stock falls, eliminating the AMT on that exercise.
- Tracking the AMT credit, which can recover AMT paid on ISO exercises in later years when regular tax exceeds AMT.
- Modeling before exercising, every year, alongside the rest of your income.
What other strategies can reduce AMT?
- Manage income around the phaseout thresholds, timing bonuses, deferred compensation, gains and Roth conversions so they do not stack in the same year.
- Maximize pre-tax retirement contributions, which reduce income for both regular tax and AMT. The 2026 401(k) limit is $24,500, plus catch-up contributions from age 50.
- Review municipal bond holdings for private activity bonds if you are near AMT.
- Coordinate charitable giving. Charitable deductions are generally allowed for AMT, and gifts of appreciated stock avoid capital gains entirely.
- Project both taxes every year. Ask your CPA to run regular tax and AMT side by side, including the effect of the state and local tax deduction, before year-end decisions are made.
Is paying AMT always bad?
Not necessarily. The AMT's top rate of 28% is below the top regular rate, so some income may be taxed more lightly within AMT. And AMT paid on ISO exercises can create credits that reduce future tax. The goal is not to avoid AMT at any cost but to make income and exercise decisions with both calculations in view.
Where should you start?
Look at line items on your most recent return: if you paid AMT, filed Form 6251 or are near the 2026 phaseout thresholds, schedule a projection before year-end. Our 2026 year-end planning guide and our article on concentrated stock positions cover related decisions. This article is general information, not tax advice; work with your CPA on your specific situation.
This article is part of our Tax Planning Guide, which collects our writing on the topic with answers to common questions.
Founder and CIO of Vistamark; as CIO of Fiducient Advisors, oversaw investment strategy for more than $260 billion in client assets. More about Matthew →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.