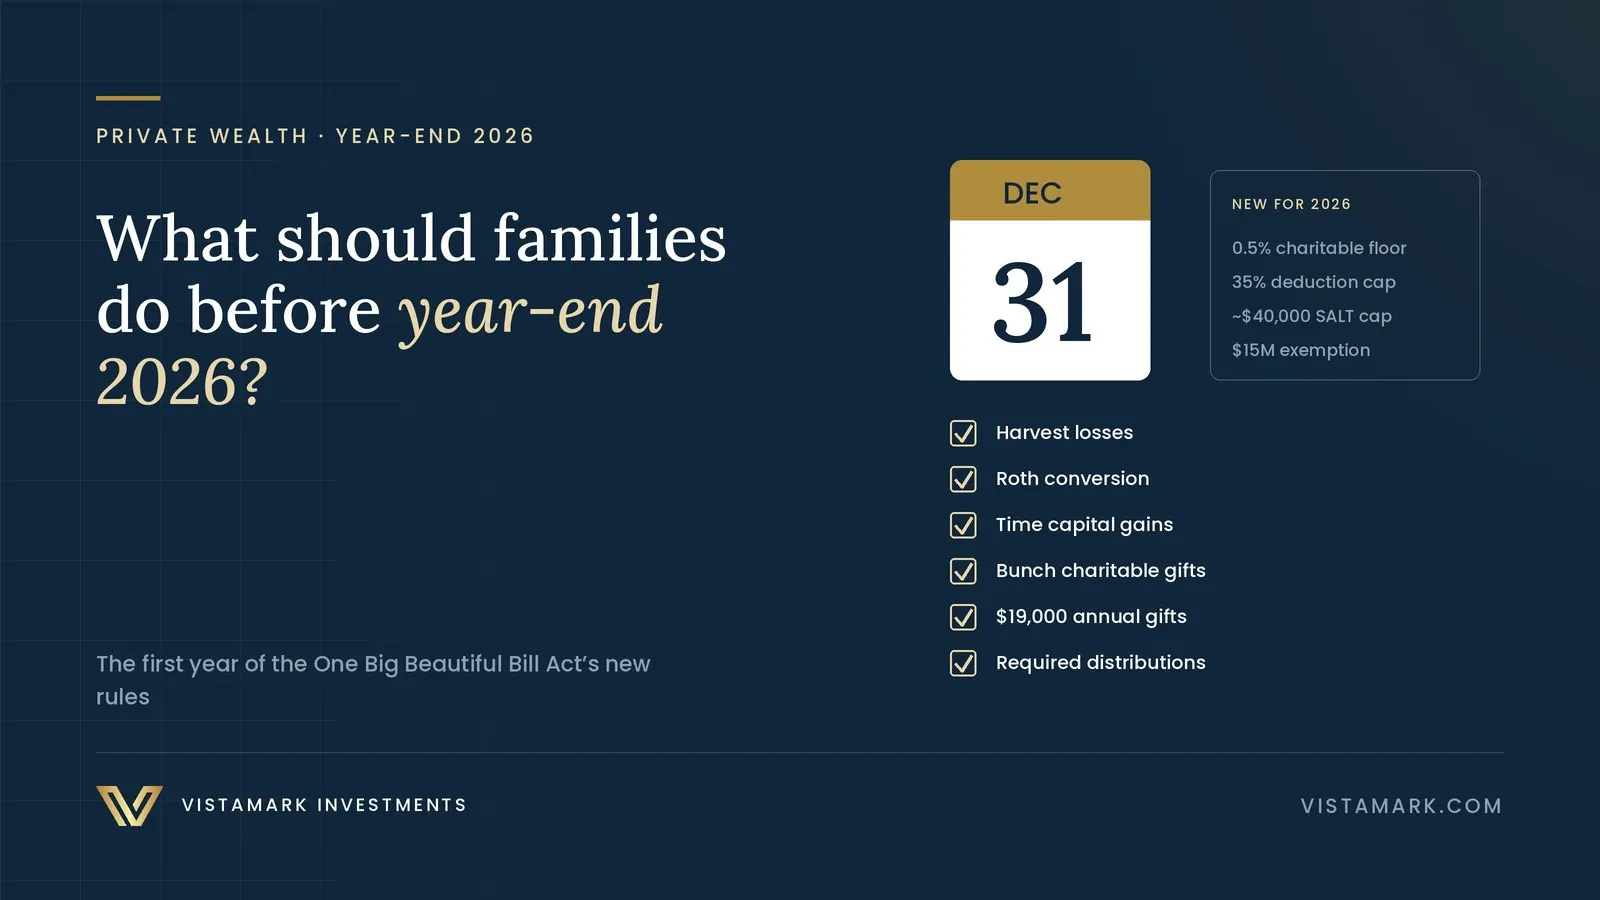
The short answer. Before December 31, 2026, a high-net-worth family should do six things: model its federal and Illinois estate tax exposure, harvest investment losses, decide which gains and Roth conversions belong in 2026, bunch charitable gifts to work around the new 0.5% floor and 35% cap on itemized deductions, use the $19,000-per-recipient gift exclusion, and confirm retirement and equity-compensation deadlines. In the Chicago area, the Illinois estate tax on estates above $4 million is the item most often missed, because it applies far below the $15 million federal exemption. Start in early November; anything that needs a new account, an appraisal or a trust signature is hard to finish in late December.
What changed for 2026?
2026 is the first year several provisions of the 2025 tax law, which the IRS now calls the Working Families Tax Cuts, apply in full (IRS). Five matter most for wealthy families:
- A charitable deduction floor. Itemizers can deduct charitable gifts only to the extent they exceed 0.5% of adjusted gross income.
- A cap on the value of itemized deductions. For taxpayers in the 37% bracket, which in 2026 starts at $768,700 of taxable income for married couples, itemized deductions reduce tax at no more than 35%.
- A higher state and local tax (SALT) cap of about $40,000, which phases back toward $10,000 for households with modified adjusted gross income above about $500,000.
- A $15 million estate and gift tax exemption per person in 2026, now permanent and indexed for inflation (IRS).
- A new deduction for non-itemizers of up to $1,000 of cash gifts to charity ($2,000 for married couples).
The practical result: for top-bracket families, how and when deductions are taken matters more than it did a year ago.
Year-end 2026 checklist at a glance
| Move | Deadline | Who leads |
|---|---|---|
| Federal and Illinois estate tax projection | Early November, so gifts and trusts can follow | Estate attorney and advisor |
| Tax-loss harvesting | Trades settled by December 31 | Investment advisor |
| Roth conversion | Completed by December 31 | CPA and advisor |
| Timing of capital gains | Sale date decides the tax year | CPA and advisor |
| Charitable gifts and donor-advised fund contributions | Received by December 31; allow extra time for stock transfers | Advisor and CPA |
| Annual exclusion gifts of $19,000 per recipient | Completed by December 31 | Family, with the attorney for gifts in trust |
| Required minimum distributions | December 31 (April 1 for a first distribution) | Advisor |
| 401(k) deferrals up to $24,500 | Final 2026 payroll | Family and employer |
| Estimated tax payments | January 15, 2027 for the fourth quarter | CPA |
Why should Illinois families start with the estate tax?
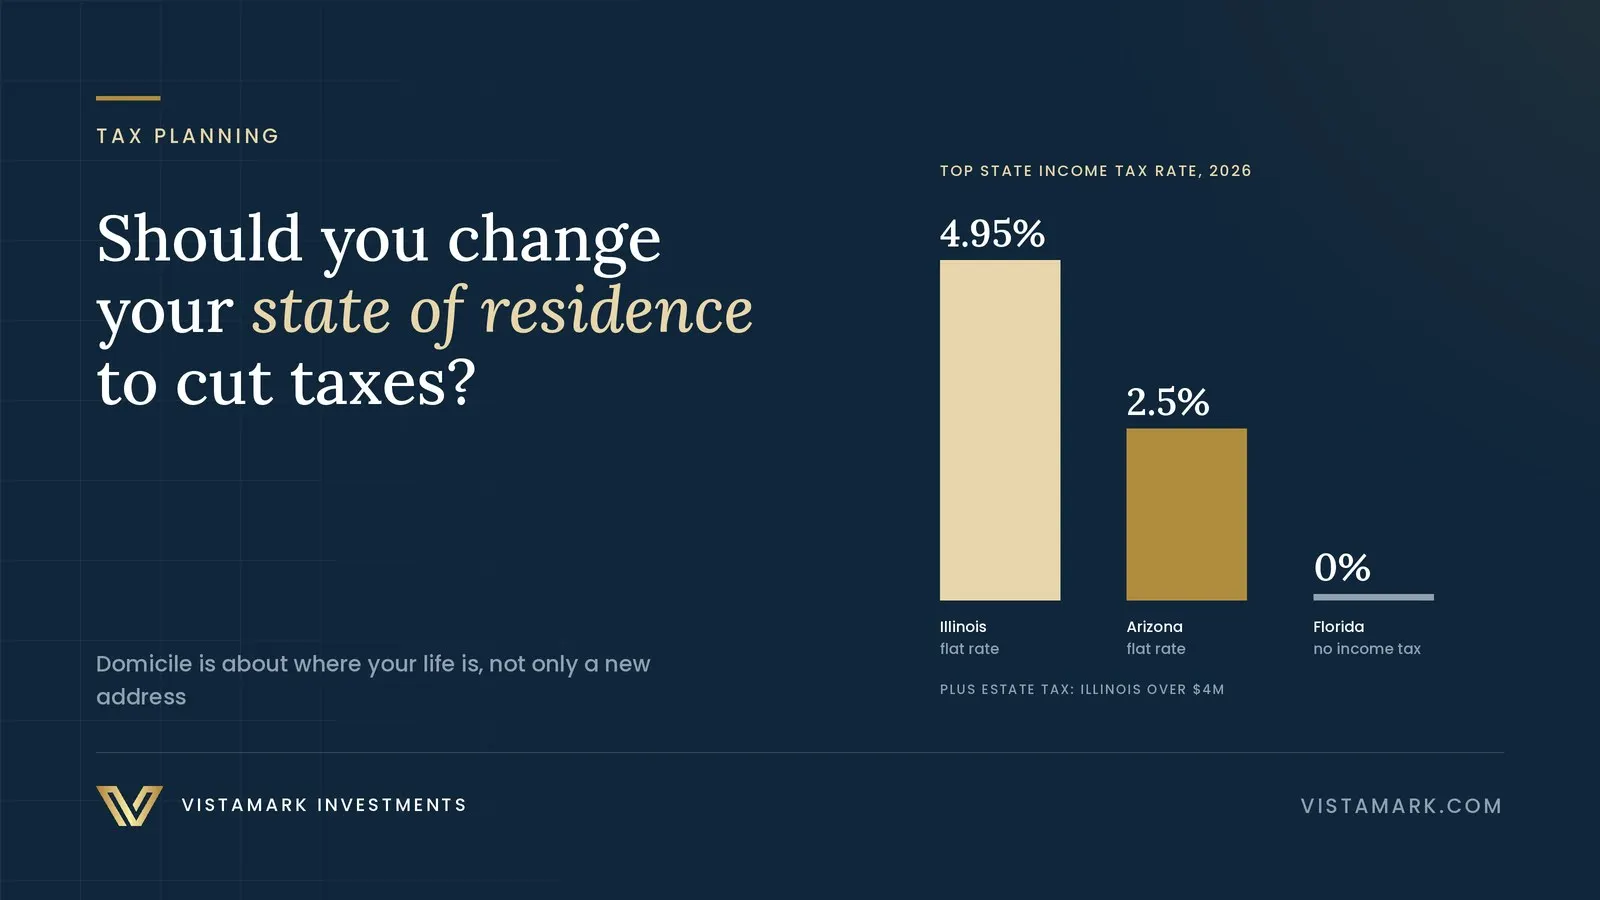
Illinois taxes estates above $4 million, and its exemption cannot be passed to a surviving spouse (Illinois Attorney General). A married Chicago couple with $12 million can owe no federal estate tax and still face a substantial Illinois bill. Year-end is the natural time to run projections for the first and second death, review beneficiary designations and trusts, and decide whether lifetime gifts, a spousal lifetime access trust or a credit shelter trust should be funded now. Our guide Essential Estate Tax Strategies for Married Couples explains the main trusts.
Should we harvest investment losses before December 31?
Yes, if you have losses and gains to offset. Realized losses offset realized gains, and up to $3,000 of excess losses a year can offset ordinary income, with the rest carried forward (IRS). Sell positions below cost and reinvest in something similar but not substantially identical to stay invested. The wash-sale rule applies across all of your accounts, including IRAs and a spouse’s accounts, so review the whole household. Families with gains coming from a business sale or a concentrated stock position can use direct indexing to generate losses throughout the year, not only in December; our article on tax-loss harvesting covers the mechanics.
Is 2026 a good year for a Roth conversion?
It can be, especially if this year’s income is lower than you expect in future years, for example after retiring but before required distributions begin. The converted amount is taxable income, so model it against your bracket, the SALT phase-down threshold, the net investment income tax and Medicare premium surcharges, which are based on income from two years earlier (see our IRMAA guide). Pay the tax from money outside the IRA when you can. Illinois does not tax retirement income, including Roth conversions, which makes conversions more attractive for Illinois residents than for residents of many other states. Conversions must be completed by December 31.
How should we time capital gains?
If you plan to sell an appreciated asset, compare selling in December with selling in January: a few weeks’ delay defers the tax by a year. If you have harvested losses, realizing some gains this year to use them can make sense. If you are charitably inclined, give the appreciated asset instead of selling it; you avoid the gain and can deduct the full market value of stock held more than a year. Business owners with a sale in view should model the timing before signing a letter of intent, because some planning, such as a charitable remainder trust or gifts of company shares, must happen before a sale is binding.
How should charitable gifts be structured this year?
The new floor and cap reward fewer, larger, well-timed gifts. Many families now bunch several years of giving into one year through a donor-advised fund, contribute appreciated securities rather than cash, and make grants to charities over time. Donors 70½ or older can give directly from an IRA through a qualified charitable distribution, which counts toward required distributions and keeps the gift out of taxable income entirely, so the floor and cap do not apply. Stock gifts and new donor-advised fund accounts take time to process, so aim to complete them by mid-December.
What gifts to family should we make before year-end?
In 2026 you can give up to $19,000 per recipient, or $38,000 for a married couple, without using any lifetime exemption, and unused exclusions do not carry forward (IRS). Tuition paid directly to a school and medical bills paid directly to a provider do not count against the exclusion. Contributions to a 529 plan can use five years of exclusions at once. Illinois has no gift tax, so lifetime gifts are one of the main ways Illinois families reduce a future state estate tax.
What retirement and benefit deadlines matter?
The key deadlines are December 31 for required minimum distributions, the final 2026 paycheck for 401(k) deferrals of up to $24,500 plus catch-up contributions, and year-end for decisions on stock option exercises and estimated tax payments.
- Required minimum distributions must be taken by December 31, except a first distribution, which can wait until April 1 of the following year (IRS).
- 401(k) and 403(b) deferrals are limited to $24,500 in 2026, plus an $8,000 catch-up at age 50 or $11,250 at ages 60 to 63 (IRS). High earners should confirm how their plan handles the new rule that their catch-up contributions be made as Roth.
- Equity compensation: review option exercises and vesting before year-end, particularly incentive stock options, which can trigger the alternative minimum tax.
- Estimated taxes: confirm that withholding and estimated payments cover the year, especially after a large gain or bonus.
Who should be in the room?
The best year-end plans are made in early November, with the investment advisor, CPA and estate attorney working from the same balance sheet and the same projections. Ask one of them to own the calendar, so each move has a person and a date.
Where does Vistamark fit?
The VistaWealth Office is the private wealth practice of Vistamark, an independent, employee- and partner-owned firm based in Chicago and Hinsdale. Each November it leads the year-end review for the families it serves: it prepares the household balance sheet and gain and loss report, runs loss harvesting and charitable stock transfers, and coordinates the estate projections and gifts with each family’s CPA and estate attorney. This article is general information, not tax or legal advice.
Sources
- Internal Revenue Service — Working Families Tax Cuts (2025 tax law provisions)
- Internal Revenue Service — What’s New, Estate and Gift Tax
- Internal Revenue Service — Frequently Asked Questions on Gift Taxes
- Internal Revenue Service — Topic No. 409, Capital Gains and Losses
- Internal Revenue Service — 401(k) Limit Increases to $24,500 for 2026
- Internal Revenue Service — Required Minimum Distributions
- Illinois Attorney General — Important Notice Regarding Illinois Estate Tax and Fact Sheet
This article is part of our Tax Planning Guide, which collects our writing on the topic with answers to common questions.
Managing Partner, VistaWealth Office™ — integrated wealth planning for executives, business owners, family offices and charities. More about William →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.