Updated October 2026. This article was first written in 2025, when the federal exemption was expected to fall by about half in 2026. The One Big Beautiful Bill Act instead set it at $15 million per person, indexed for inflation, with no scheduled expiration. The strategies below reflect the current law.
For married couples with significant wealth, estate planning is less about a looming deadline than it was a year ago and more about using the tools that move future growth to the next generation efficiently, minimize state estate tax and keep control where the family wants it.
How much can a married couple pass free of federal estate tax?
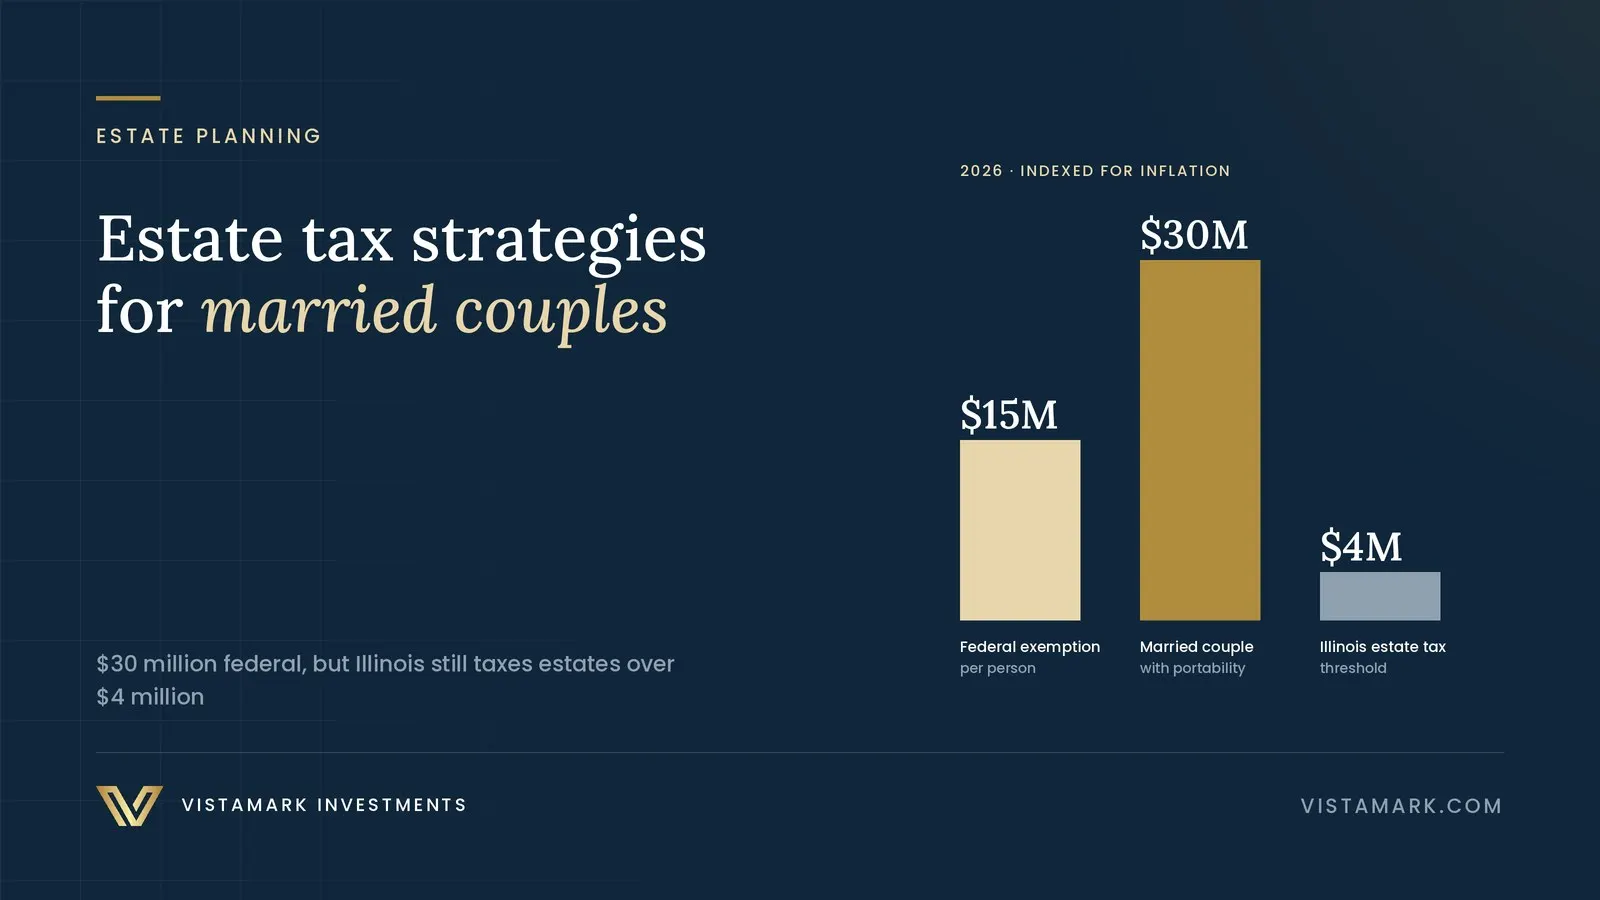
In 2026, each person can transfer $15 million during life or at death without federal estate or gift tax, so a married couple can shelter $30 million. Transfers between spouses who are U.S. citizens are unlimited through the marital deduction. Amounts above the exemption are taxed at 40%. The annual gift exclusion, which does not use any exemption, is $19,000 per recipient, or $38,000 for a married couple.
What about state estate taxes?
For many couples, the state tax is the bigger issue. Illinois taxes estates above $4 million, does not allow portability between spouses and does not adjust its threshold for inflation. A married Illinois couple with $12 million can owe no federal tax but significant Illinois tax unless their plan uses both spouses' Illinois exemptions, typically through a credit shelter or bypass trust at the first death. Several other states impose their own estate or inheritance taxes; Arizona and Florida have none.
What is portability, and should you elect it?
Portability lets a surviving spouse use the deceased spouse's unused federal exemption. It is not automatic: the executor must file a federal estate tax return (Form 706) to elect it, even if no tax is owed. Skipping that filing can waste up to $15 million of exemption. Portability applies only to the federal exemption, not to Illinois, and it does not carry over the deceased spouse's generation-skipping transfer exemption or shelter growth after the first death, which is why many plans still use trusts at the first death.
Which strategies matter most for larger estates?
- Lifetime gifts of appreciating assets. A gift removes all future growth from the estate. Gifting business interests or private investments before they appreciate can save far more tax than their current value suggests. The trade-off is that gifted assets do not receive a step-up in basis at death.
- Spousal lifetime access trusts (SLATs). One spouse makes a gift to a trust for the other spouse and descendants, using exemption while keeping indirect access. Each spouse can create one, but they must differ meaningfully to avoid being treated as reciprocal.
- Grantor retained annuity trusts (GRATs). These shift appreciation above an IRS-set rate to heirs with little or no gift tax and work well for volatile or fast-growing assets.
- Irrevocable life insurance trusts (ILITs). These keep insurance proceeds out of the estate and provide liquidity for estate taxes, especially useful for Illinois tax. See our life insurance guide.
- Family limited partnerships and LLCs. These centralize management and can support valuation discounts for minority interests given to heirs, which the IRS scrutinizes closely.
- Dynasty trusts. These use the generation-skipping exemption to keep assets out of the taxable estates of children and grandchildren.
- Charitable trusts. Charitable remainder and lead trusts combine giving with income or transfer planning. See our guide to charitable remainder trusts.
How do disclaimers and Clayton elections add flexibility?
Plans can be built to adapt after the first death. A disclaimer lets the surviving spouse refuse an inheritance so it passes to a trust, using the deceased spouse's exemption. A Clayton election lets the executor decide how much property qualifies for the marital deduction. Both allow the family to choose the best tax result based on the law, asset values and needs at that time, rather than guessing years in advance.
Does "permanent" mean the exemption will never change?
No. It means there is no built-in expiration date. Any future Congress can change the exemption, as it has many times before. Plans should work under a range of outcomes, which is another reason to favor flexible provisions over rigid formulas.
What should married couples do now?
- Review wills, trusts and beneficiary designations to make sure they reflect the $15 million exemption and your state's rules.
- Estimate your estate under both federal and state law, including growth over the coming decades.
- Use annual exclusion gifts each year; unused exclusions do not carry forward.
- Identify assets likely to appreciate that could move out of the estate through gifts or trusts.
- Make sure the surviving spouse's executor knows to elect portability.
Estate planning is legal work that requires an experienced attorney. For the broader picture, see our guide to planning with the permanent exemption. The VistaWealth Office coordinates estate plans with each family's investments, insurance and taxes.
This article is part of our Estate Planning Guide, which collects our writing on the topic with answers to common questions.
Founder and CIO of Vistamark; as CIO of Fiducient Advisors, oversaw investment strategy for more than $260 billion in client assets. More about Matthew →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.