Many of the families we work with split their time between the Chicago area and Arizona, and the question comes up often: should we make Arizona, or Florida, or another state our legal home? The tax difference can be substantial. But a change of residence is not a change of address. It is a change of life, and states such as Illinois are well practiced at challenging moves that look like paperwork.
How much can a move save?
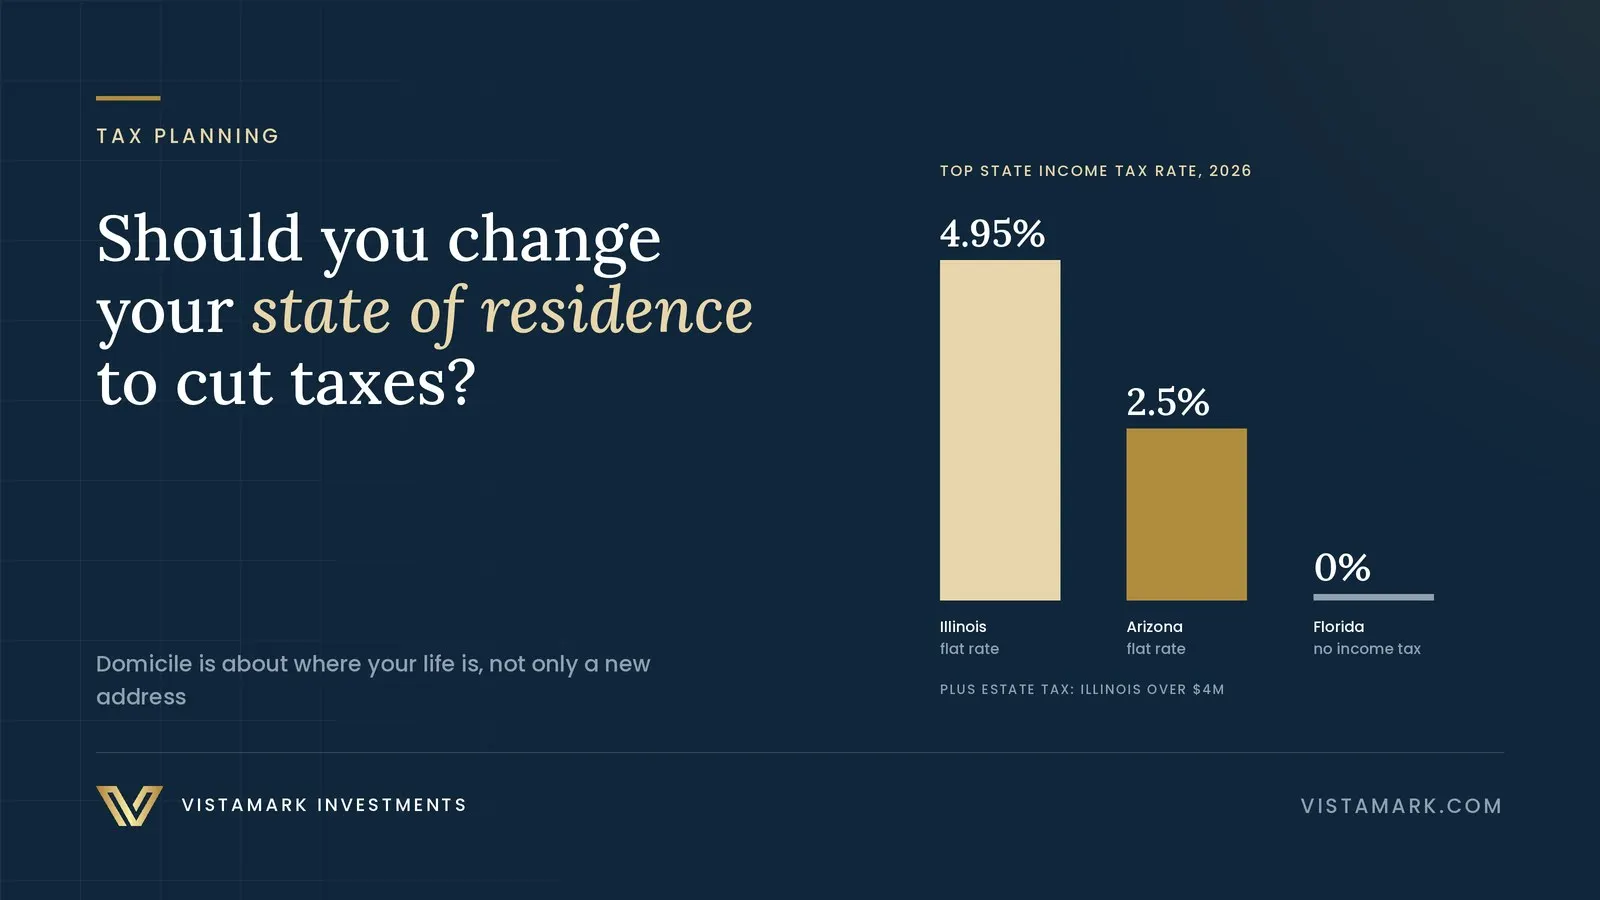
It depends on the states and the family's income and estate. Illinois taxes income at a flat 4.95% and taxes estates above $4 million. Arizona's flat income tax is 2.5% and it has no estate tax. Florida, Texas and several other states have no personal income tax at all. For a family with large investment income, a business sale on the horizon or an estate well above $4 million, the combined difference over a lifetime can be significant. For a family with modest income and a smaller estate, it may not justify uprooting.
What is the difference between residence and domicile?
You can have several residences but only one domicile: the place you consider your permanent home and intend to return to. Domicile generally determines which state can tax all of your income and your estate. Many states also treat you as a statutory resident, taxable on all income, if you keep a home there and spend more than a set number of days in the state, even if your domicile is elsewhere.
What do states look at to decide where you live?
- Home: which home is larger, more valuable and more used, and whether you sold or kept the old one.
- Time: where you actually spend your days, documented by phone records, credit card activity and travel.
- Family: where your spouse and minor children live and go to school.
- Business: where you work, run your business and hold board seats.
- Near and dear items: where your valuable possessions, art, pets and heirlooms are kept.
- Formal ties: driver's license, voter registration, vehicle registration, will, doctors and professional advisors.
Formal ties alone are not enough. Auditors look at the overall pattern of your life.
What are the most common mistakes?
- Changing the driver's license and voter registration but keeping the same life, clubs and doctors in the old state.
- Not tracking days. A calendar or app that records where you are each day is invaluable in an audit.
- Selling a business or realizing a large gain right after moving, which invites scrutiny of the timing.
- Leaving trusts, entities or real estate in the old state without considering whether that state can still tax them.
- Forgetting that the old state may still tax income earned there, such as wages or business income sourced to that state.
How should a family plan a move?
- Model the savings with your CPA, including income, capital gains and estate taxes, before deciding.
- Plan the timing around any major transaction, ideally establishing the new domicile well before a sale.
- Move your life, not just your paperwork: home, time, family, possessions and community ties.
- Update every document, including wills, trusts, powers of attorney and beneficiary designations, under the new state's law.
- Keep records for several years, because residency audits often look back.
Is a move worth it?
For some families, clearly yes; for others, the savings do not outweigh the change in daily life. The decision should come from a full picture of the family's taxes, plans and preferences, not from a single tax rate. Our Phoenix and Chicago advisor guides cover the planning issues in each state, and the VistaWealth Office serves families in both.
This article is part of our Tax Planning Guide, which collects our writing on the topic with answers to common questions.
Founder and CIO of Vistamark; as CIO of Fiducient Advisors, oversaw investment strategy for more than $260 billion in client assets. More about Matthew →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.