The short answer. At $25 million and up, choose an independent fiduciary that does three things most advisors do not: plans around Illinois’s $4 million estate tax exemption as well as the federal one, manages your wealth after tax across every account, trust and entity, and brings written diligence to private investments. Insist that a senior person does the work, that every fee is stated in dollars, and that your assets stay in your name at an independent custodian. Interview three firms with the same questions and compare the answers side by side.
Why does $25 million change what you need from an advisor?
Chicago has no shortage of advisors. It ranked tenth among the world’s wealthiest cities in 2025, with about 127,100 millionaires (Henley & Partners, via Time Out Chicago). But the work changes at $25 million. The family usually holds assets across several custodians, trusts and entities; owns private funds, real estate or an operating business; faces estate tax decisions that are worth millions; and has more than one generation at the table. Picking stocks and funds becomes the smallest part of the job. Coordination, tax and governance become the largest.
What makes Illinois different?
- Estate tax. The federal exemption is $15 million per person in 2026 and was made permanent by the 2025 tax law (Faegre Drinker). Illinois taxes estates above $4 million, and its exemption is not portable between spouses. A married couple with $25 million can owe little or no federal estate tax and still face a large Illinois bill unless their plan uses both spouses’ exemptions, usually through trusts. Our estate planning with the permanent $15 million exemption article covers the federal side.
- Income tax. Illinois taxes individual income at a flat 4.95% (Illinois Department of Revenue), on top of federal tax. Asset location, loss harvesting and the timing of gains all matter more when every dollar of income is taxed twice.
- Residency. Many Chicago families spend winters in Arizona or Florida, neither of which has an estate tax. A change of domicile can change the plan, but only with real evidence of a move. See Should You Change Your State of Residence to Cut Taxes?
What should you compare?
| Criterion | Ask | What a good answer looks like |
|---|---|---|
| Fiduciary duty | “Are you a fiduciary on every account, at all times, in writing?” | Yes, in the advisory agreement, with no brokerage accounts on the side |
| Independence | “Who owns the firm, and do you sell any products of your own?” | Owned by the people who advise you; no proprietary funds |
| Fees | “What will I pay in dollars, including fund and private-investment fees?” | One advisory fee and a written estimate of every other cost |
| Who does the work | “Who will I meet with, and how many families does each of them serve?” | A senior, credentialed professional who builds your portfolio, not only a relationship manager |
| Tax and estate integration | “Show me how you would plan around the Illinois exemption for us.” | A specific answer that names your trusts and accounts, and a plan to work with your attorney and CPA |
| After-tax management | “Do you report returns after tax, across all our accounts?” | Yes, with asset location and loss harvesting across taxable, trust and retirement accounts |
| Private investments | “How do you diligence private funds, and how do you plan for capital calls?” | Written diligence on every fund, sizing to your liquidity needs, and a pacing plan |
| Reporting | “Can I see a sample consolidated report?” | One report covering every account, entity and private fund, including assets the firm does not manage |
| Custody | “Where are my assets held, and in whose name?” | At an independent qualified custodian, in your name |
| Regulatory record | Check the SEC’s Investment Adviser Public Disclosure site and FINRA BrokerCheck | A clean record and a Form ADV that matches what you were told |
What are the red flags?
- Fees quoted only as a percentage, or not at all for private investments and funds.
- A portfolio that looks like the firm’s model for everyone, regardless of your taxes and trusts.
- Recommendations that favor the firm’s own funds, insurance or lending.
- No plan to talk to your CPA or estate attorney.
- A senior person at the pitch meeting who you never see again.
Do you need a family office or a wealth manager?
At $25 million, most families need family office services: one consolidated view, coordinated advisors, written policy and governance. Few need to build an office of their own, which typically makes sense only at far higher levels of wealth. Our article Family Office vs. Wealth Manager explains the difference and what to ask firms that use the label.
How should you run the search?
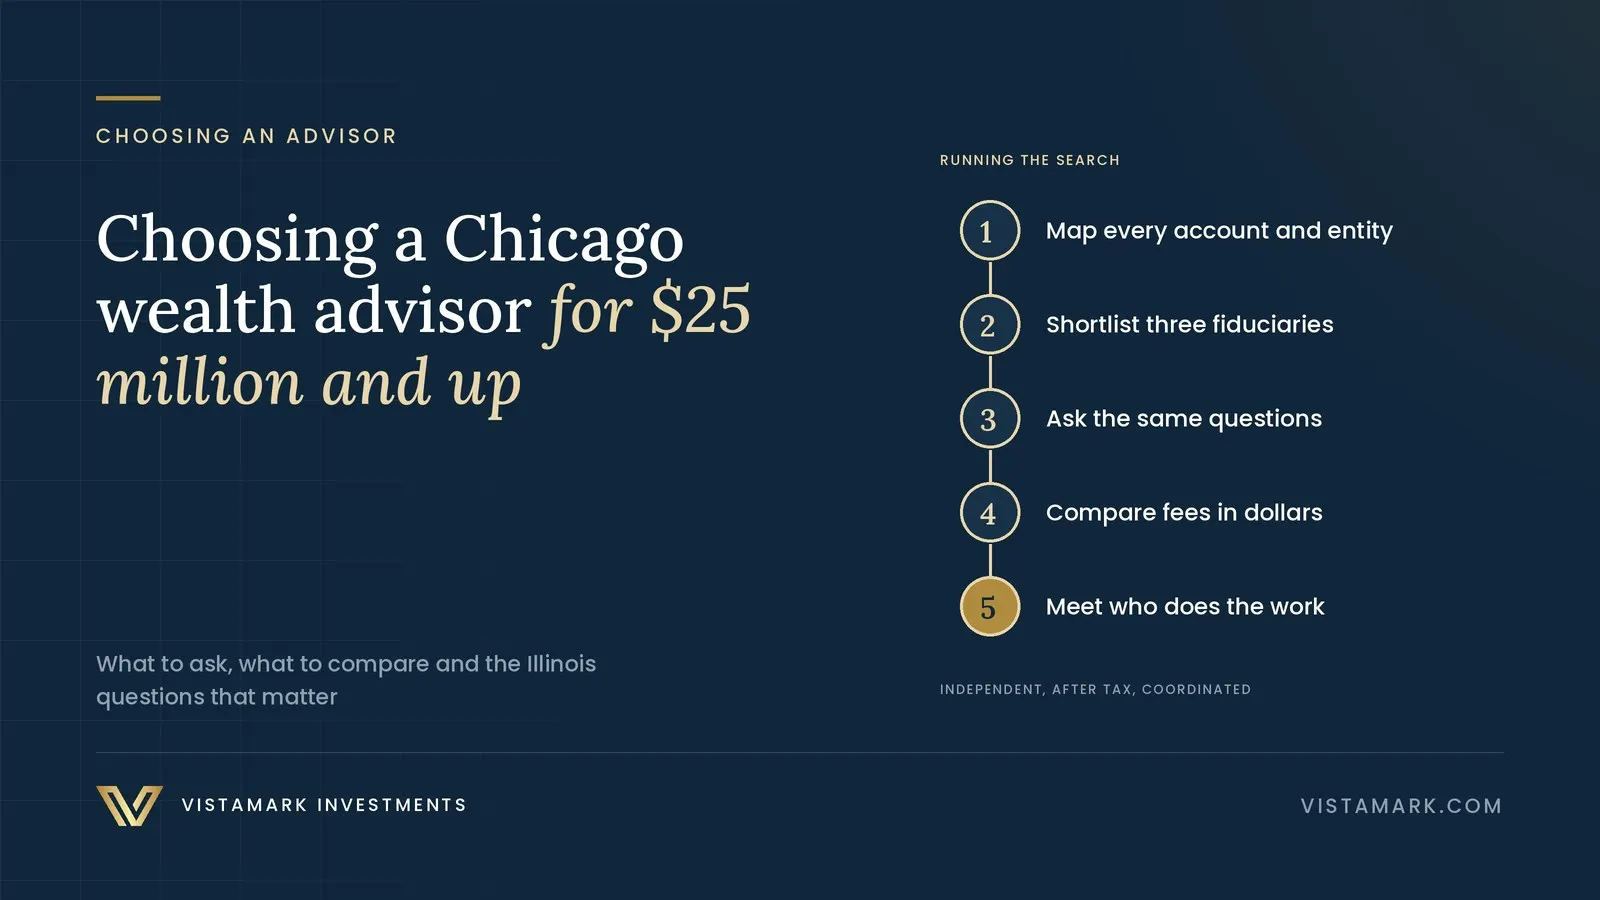
- Write one page listing every account, trust, entity and advisor you have today.
- Shortlist three independent, fee-only fiduciaries, and check each on the SEC’s adviser site.
- Send every firm the same questions from the table above, and ask for a fee estimate in dollars on your actual balance sheet.
- Ask for a sample consolidated report and a sample investment policy statement.
- Meet the people who would do the work, and ask them how they would handle your estate plan.
Our original guide to selecting a Chicago-area financial advisor covers the basics for any household, and How Should a Family Coordinate Its Advisors? covers the work that follows the decision.
Where does Vistamark fit?
Vistamark is an independent, SEC-registered investment adviser, 100% employee- and partner-owned, with offices in Chicago’s Gold Coast, Hinsdale and Phoenix. Through the VistaWealth Office, we bring the investment process our partners use for institutions to Chicago families, and add family office services: investment policy, consolidated reporting, private-markets diligence and coordination with your tax and estate advisors. We have no minimum and charge one advisory fee, asset-based or flat, described on Our fees. We prefer Charles Schwab as custodian and can work with others. The first conversation is with a partner, at no cost.
Sources
- Time Out Chicago — Chicago Is Named One of the Wealthiest Cities in the World (April 9, 2025), on the Henley & Partners World’s Wealthiest Cities Report 2025
- Faegre Drinker — 2026 Estate Tax Exemption and Planning Considerations (January 12, 2026)
- Illinois Department of Revenue — Income Tax Rates
- U.S. Securities and Exchange Commission — Investment Adviser Public Disclosure
This article is part of our Family Governance Guide, which collects our writing on the topic with answers to common questions.
Managing Partner and Founder; advises families, business owners and family offices through the VistaWealth Office™ and leads Vistamark’s private markets research. More about Sean →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.