The short answer. In 2026 Illinois taxes the estate of a resident worth more than $4 million, far below the $15 million federal exemption. The Illinois exclusion is not indexed for inflation and cannot pass to a surviving spouse, so a Chicago-area family can owe Illinois estate tax while owing nothing to the IRS. Married couples who plan ahead, usually with a credit shelter trust that uses each spouse’s $4 million and a separate Illinois QTIP election, can often reduce the bill substantially or avoid it.
What is the Illinois estate tax exemption in 2026?
The Illinois estate tax exclusion is $4 million per person in 2026, the same amount it has been since 2013, because Illinois law does not index it for inflation. The Illinois Attorney General describes the $4 million as “a taxable threshold and not a credit against tax” (Illinois Attorney General).
The threshold is measured on the gross estate plus adjusted taxable gifts made during life. The house, retirement accounts, life insurance owned by the decedent and any business interest all count, which is why many Chicago and DuPage County families who do not think of themselves as wealthy cross it.
Who has to pay the Illinois estate tax?
The Illinois estate tax applies to the estate of an Illinois resident whose gross estate plus adjusted taxable gifts exceeds $4 million, and to a nonresident whose estate includes Illinois real estate or tangible property located in Illinois. A nonresident’s tax is prorated to the share of the estate located in Illinois (Illinois Attorney General).
A family that retired to Arizona or Florida but kept a house in Winnetka or Hinsdale should plan for that. The executor files the Illinois Estate and Generation-Skipping Transfer Tax Return, Form 700, with the Attorney General, and the return and payment are due nine months after the date of death (Illinois Attorney General, Form 700).
How is the Illinois estate tax different from the federal estate tax?
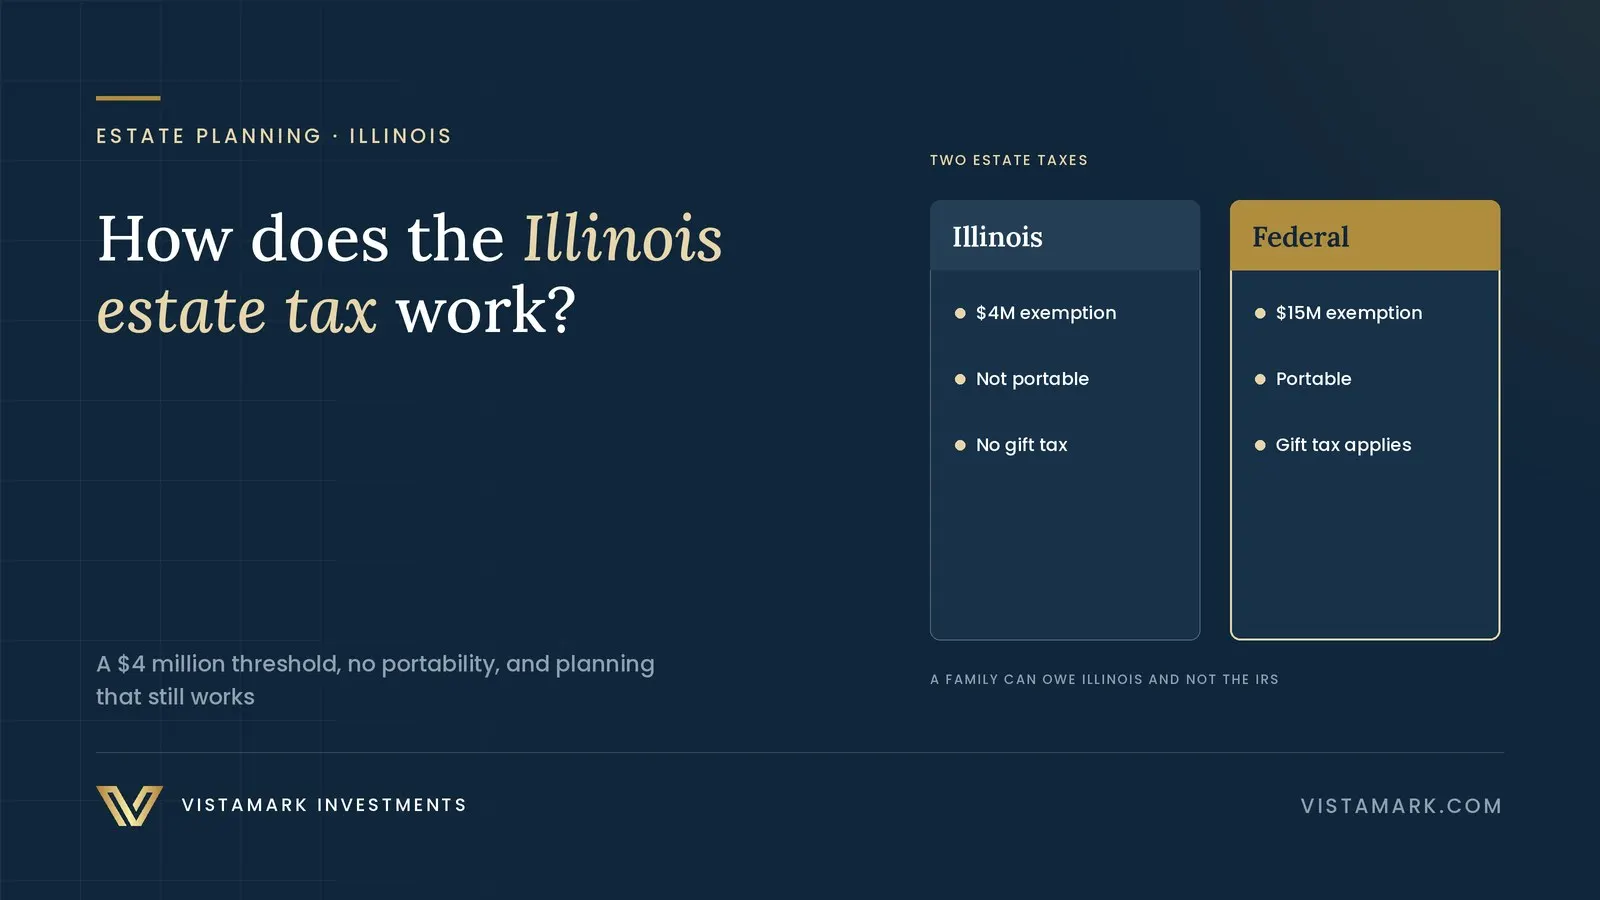
The Illinois estate tax starts at $4 million per person, is not indexed for inflation and is not portable between spouses, while the federal estate tax exemption is $15 million per person in 2026, is indexed and is portable. Illinois has no gift tax; the federal gift tax shares the federal exemption. A family can therefore owe Illinois and not the IRS.
| Illinois | Federal | |
|---|---|---|
| Exemption (2026) | $4 million per person | $15 million per person |
| Indexed for inflation | No | Yes |
| Portable to a surviving spouse | No | Yes, with a timely election |
| Gift tax | None | Yes, sharing the same exemption |
| Tax on a $5 million estate (2026) | $285,714 (Attorney General example) | $0, below the exemption |
| Return and due date | Form 700, nine months after death | Form 706, nine months after death |
The 2025 federal tax law, the One Big Beautiful Bill Act, set the federal exemption at $15 million for 2026 and indexed it afterward (IRS), but it did not change the Illinois tax, which is set by the Illinois Estate and Generation-Skipping Transfer Tax Act (35 ILCS 405). Illinois figures its tax with an “interrelated calculation,” because the Illinois tax is itself deductible in arriving at the taxable estate it is based on; the Attorney General publishes an online calculator for it.
Can a surviving spouse use the first spouse’s Illinois exemption?
No. Unlike the federal estate tax, Illinois has no portability, so a $4 million Illinois exclusion that the first spouse does not use at death is lost. Couples who leave everything outright to each other typically waste one exclusion and expose millions of dollars more to Illinois estate tax at the second death.
Worked example. A Hinsdale couple owns $9 million, split evenly, and their wills leave everything outright to each other. At the first death there is no tax because of the unlimited marital deduction. At the second death the survivor’s $9 million estate has only one $4 million exclusion, leaving about $5 million over the threshold. If instead the first spouse’s will sends $4 million into a credit shelter trust for the survivor, the survivor’s estate at death is about $5 million, only $1 million over the threshold, and the $4 million in the trust, plus its growth, passes to the children free of Illinois estate tax.
| Plan | Survivor’s estate at second death | Amount over the $4 million exclusion |
|---|---|---|
| Everything outright to the spouse | About $9 million | About $5 million |
| $4 million credit shelter trust at first death | About $5 million | About $1 million |
The figures ignore growth and spending and are illustrative. A credit shelter (bypass) trust still lets the survivor receive income and, within limits, principal, but the trust is not part of the survivor’s estate. It works only if the first spouse to die owns enough in his or her own name to fund it, so joint accounts and a house held in joint tenancy often need to be retitled.
What is the Illinois QTIP election?
The Illinois QTIP election lets an executor treat property in a qualifying trust for the surviving spouse as marital-deduction property for Illinois purposes, in addition to any federal QTIP election. It allows the first estate to use far more than $4 million of federal exemption while keeping the Illinois tax at zero, deferring the Illinois tax on the excess until the second death (Illinois Attorney General).
The election is made on a timely filed Form 700. Wills and trusts drafted before the federal and Illinois exemptions diverged, or drafted without Illinois in mind, may not give the executor this flexibility, which is a common reason for an Illinois-specific estate plan review.
How can a Chicago family reduce or avoid the Illinois estate tax?
A Chicago-area family can reduce or avoid the Illinois estate tax by using both spouses’ $4 million exclusions through a credit shelter trust, making lifetime gifts (Illinois has no gift tax), holding life insurance in an irrevocable life insurance trust (ILIT) and leaving assets to charity. Each move shrinks the estate Illinois taxes at death.
- Lifetime gifts. Assets given away during life generally leave the Illinois taxable estate, along with their future growth. Prior taxable gifts still count toward the $4 million filing threshold, and gifts made close to death deserve an attorney’s review.
- An irrevocable life insurance trust (ILIT). Life insurance owned personally is part of the estate; insurance owned by an ILIT generally is not. Our article How Should Wealthy Families Use Life Insurance? explains the structure.
- Charitable gifts and trusts. Gifts to charity at death are deductible for Illinois as well as federally. A charitable remainder trust can also move appreciated assets out of the estate while paying income for life.
- Retitling assets between spouses so each spouse can fund a credit shelter trust.
- Changing your domicile. Moving to a state with no estate tax removes Illinois tax on everything except Illinois real estate and tangible property, but only if the move is real. Our article Should You Change Your State of Residence to Cut Taxes? covers the tests Illinois applies.
Which Chicago-area families should review their estate plans now?
Chicago-area families should review their estate plans now if a married couple’s combined assets exceed $4 million, if their wills leave everything outright to a spouse, or if they rely on federal portability, which does nothing for Illinois. Families who moved away but still own Illinois real estate should review too.
- Couples with combined assets above $4 million, counting the house, retirement accounts, life insurance and any business interest.
- Anyone whose documents predate the current $15 million federal exemption or never mention Illinois.
- Families who have moved out of Illinois but still own a home or land in Cook, DuPage, Lake or another Illinois county.
- Business owners whose company value would push the estate well past $4 million.
Where does Vistamark fit?
The VistaWealth Office is the private wealth practice of Vistamark, an independent, employee- and partner-owned firm headquartered in Hinsdale, Illinois, in the Chicago area. It does not draft wills or trusts; it works alongside a family’s estate attorney and CPA to map what each spouse owns and how it is titled, estimate the Illinois and federal estate tax under the current plan, and keep the investment plan, trusts and beneficiary designations aligned as assets grow.
Our guide How to Choose a Chicago Wealth Advisor for $25 Million and Up explains how to compare firms. Vistamark has no minimum. This article is general information, not legal or tax advice.
Sources
Market Compass · weekly
Get the Compass by email
One concise recap of the week’s market-moving events and what to watch next, written by our CIO at the end of each market week.
Managing Partner, VistaWealth Office™ — integrated wealth planning for executives, business owners, family offices and charities. More about William →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.