The short answer. Before December 31, 2026, most Chicago-area families should give appreciated stock rather than cash, consider bunching several years of gifts into one year through a donor-advised fund, and, from age 70½, give up to $111,000 per person directly from an IRA. Starting in 2026, itemizers can deduct charitable gifts only to the extent they exceed 0.5% of adjusted gross income, and top-bracket taxpayers get at most 35 cents of benefit per dollar deducted. Fewer, larger, well-structured gifts now beat many small ones.
What changed for charitable deductions in 2026?
The One Big Beautiful Bill Act changed the charitable deduction for 2026 and later years in three ways: a 0.5%-of-income floor for itemizers, a cap that limits top-bracket taxpayers to about 35 cents of benefit per dollar deducted, and a new deduction for people who do not itemize. Together they reward concentrating gifts and choosing the right asset to give.
- A 0.5% floor. Itemized charitable gifts count only to the extent they exceed 0.5% of the donor’s contribution base, essentially adjusted gross income (26 U.S.C. § 170). For a household with $1 million of income, the first $5,000 of gifts each year produces no deduction.
- A 35% cap on the value of itemized deductions for taxpayers in the 37% bracket, through a reduction of 2/37 of itemized deductions (26 U.S.C. § 68).
- A deduction for non-itemizers of up to $1,000, or $2,000 for married couples filing jointly, for cash gifts to public charities. Gifts to donor-advised funds and supporting organizations do not qualify (26 U.S.C. § 170(p)).
Our earlier article on what the new rules mean for nonprofits and donors covers the law in more detail.
Is it better to donate appreciated stock or cash?
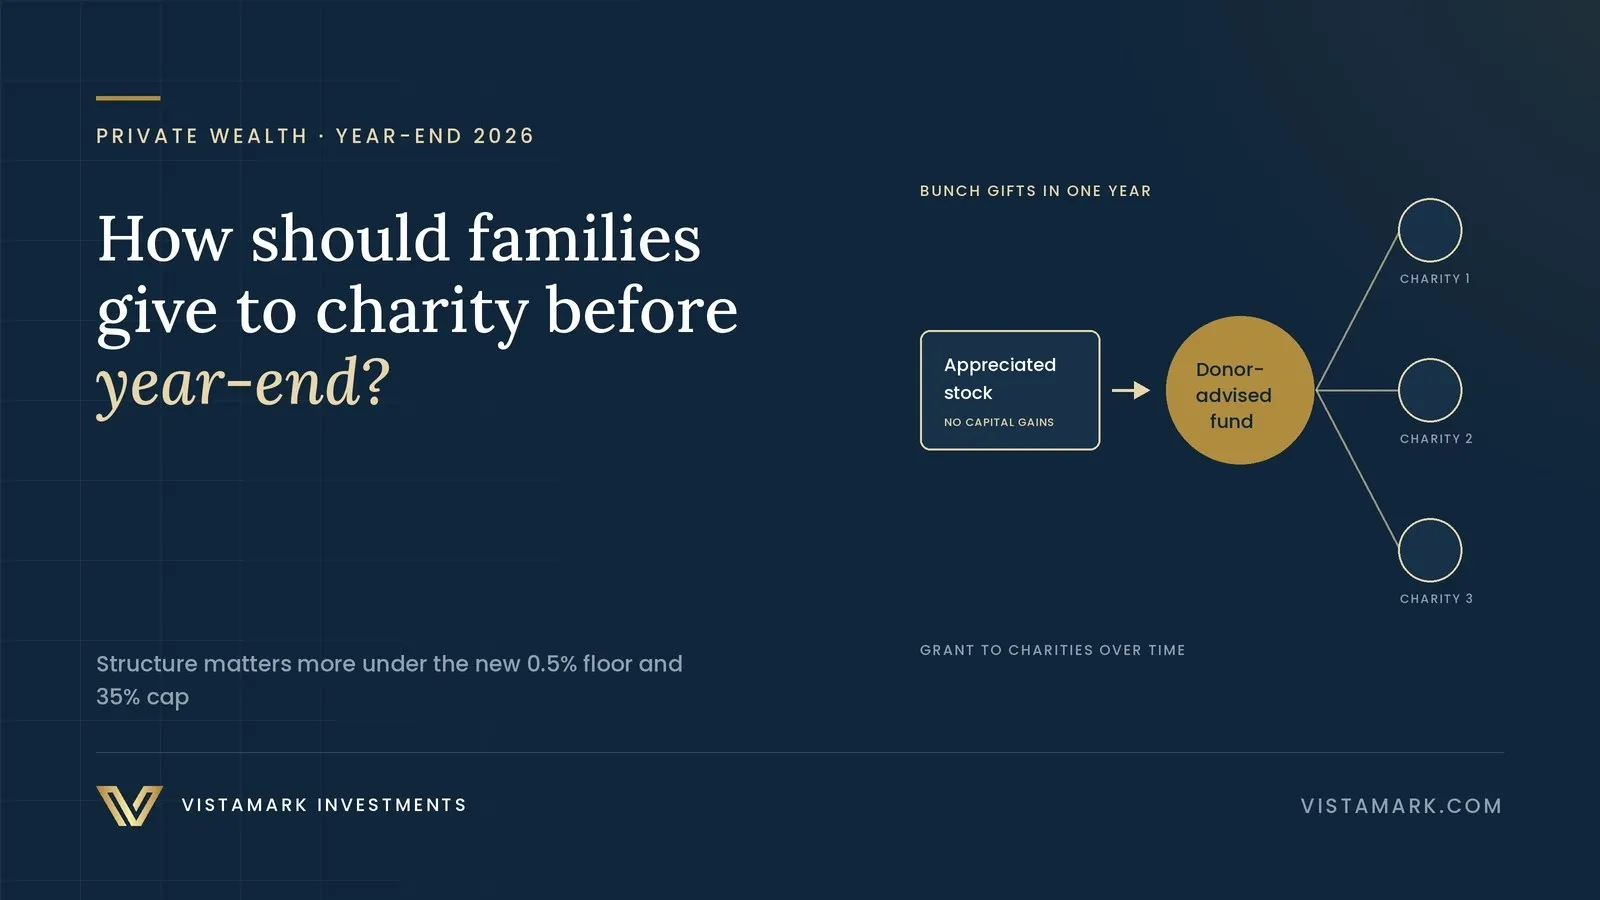
Appreciated stock is usually better than cash. When you give publicly traded stock held for more than a year to a public charity or donor-advised fund, you generally deduct its full market value and never pay capital gains tax on the appreciation, which a sale followed by a cash gift would trigger (IRS Publication 526).
Gifts of appreciated stock to public charities and donor-advised funds are deductible up to 30% of adjusted gross income, compared with 60% for cash; anything above the limit carries forward for five years. If you like the position, give the low-basis shares and use the cash you would have given to buy the stock back at a higher cost basis.
What is bunching, and does it still make sense in 2026?
Bunching means making several years of planned gifts in a single tax year, usually into a donor-advised fund, and then recommending grants to charities over the following years. In 2026 bunching makes more sense than before, because the 0.5% floor is paid once in the bunching year instead of every year, and a large gift is more likely to lift total itemized deductions above the standard deduction.
Worked example. A Winnetka couple with $1 million of adjusted gross income gives about $30,000 a year and holds stock worth $90,000 that cost $30,000. They itemize every year. The table compares three years of cash gifts with one bunched gift of stock to a donor-advised fund in 2026.
| $30,000 cash each year, 2026–2028 | $90,000 of stock to a donor-advised fund in 2026 | |
|---|---|---|
| Lost to the 0.5% floor | $15,000 ($5,000 a year) | $5,000 (once) |
| Deductible gifts | $75,000 | $85,000 |
| Capital gain avoided | $0 | $60,000 |
| Federal and Illinois tax on that gain avoided | $0 | About $17,250 (20% + 3.8% federal, 4.95% Illinois) |
The charities receive the same $90,000 either way, through grants from the fund in 2026, 2027 and 2028. The figures are illustrative and use the top 20% federal long-term capital gains rate, which applies at this couple’s income, and the 3.8% net investment income tax (IRS).
Should you use a donor-advised fund or a private foundation?
A donor-advised fund suits most families who want simplicity, larger deduction limits and privacy, while a private foundation suits families who want control, a lasting institution and a role for the next generation and can accept the cost and public reporting. Many Chicago families use both.
| Donor-advised fund | Private foundation | |
|---|---|---|
| Deduction limit, appreciated stock | 30% of income, full market value | 20% of income |
| Annual payout rule | None | About 5% of the foundation’s investment assets |
| Tax on investment income | None | 1.39% excise tax |
| Control and staff | You recommend grants | Family board decides; can hire |
The 5% minimum distribution and 1.39% excise tax come from the Internal Revenue Code (26 U.S.C. § 4942; 26 U.S.C. § 4940).
Who should use a qualified charitable distribution in 2026?
Anyone 70½ or older who owns an IRA and gives to charity should consider a qualified charitable distribution (QCD), which sends up to $111,000 per person in 2026 directly from the IRA to a charity (IRS Notice 2025-67). The amount is excluded from income, and from age 73 it counts toward the required minimum distribution.
Keeping the gift out of adjusted gross income also avoids the 0.5% floor and can keep income below Medicare premium thresholds; our IRMAA guide lists them. QCDs cannot go to donor-advised funds, supporting organizations or most private foundations (IRS Publication 590-B).
Does Illinois give a tax break for charitable donations?
Illinois income tax starts from federal adjusted gross income and has no itemized deduction for charitable gifts, so a cash gift saves nothing at the state level. Giving appreciated stock does save Illinois tax, because the gain never enters adjusted gross income and so escapes Illinois’s 4.95% rate as well as federal capital gains tax (Illinois Department of Revenue).
A QCD offers no extra Illinois benefit, because Illinois already exempts IRA distributions from its income tax. For families whose giving continues at death, Illinois also allows a charitable deduction against its estate tax on estates above $4 million.
What is the deadline for 2026 charitable gifts?
A gift counts for 2026 only if it is completed by December 31, 2026. A check counts when mailed, a credit card gift when charged, and a stock gift when the shares arrive in the charity’s or fund’s account, which can take a week or more (IRS Publication 526).
New donor-advised fund accounts, QCDs and transfers of shares held at a different custodian take longest, so start them by early December.
What is the year-end giving checklist?
A family planning its 2026 gifts should total what it has already given, compare it with 0.5% of expected income, choose the assets to give and allow time for transfers. The steps below cover the decisions in order.
- Total gifts made so far in 2026 and compare them with 0.5% of expected adjusted gross income.
- Decide whether 2026 is a bunching year, especially if income is unusually high from a business sale, bonus or large capital gain.
- Pick appreciated securities held more than a year to give instead of cash.
- If you are 70½ or older, ask your IRA custodian to send QCDs directly to the charities.
- For larger, long-term plans, consider a charitable remainder trust, which usually takes more than a few weeks to set up.
- Get a written acknowledgment for every gift of $250 or more, and a qualified appraisal for non-cash gifts over $5,000 other than publicly traded securities (IRS Publication 526).
Our 2026 year-end tax checklist covers the other December 31 deadlines.
Where does Vistamark fit?
The VistaWealth Office is the private wealth practice of Vistamark, an independent, employee- and partner-owned firm headquartered in Hinsdale, Illinois, in the Chicago area. For charitable giving, it identifies which holdings carry the largest gains, models whether bunching pays for the family’s income, coordinates QCDs and stock transfers with the custodian before year-end, and works with the family’s CPA on the deduction. Vistamark also advises foundations and nonprofits, so it can help a family that runs its own foundation. This article is general information, not tax or legal advice.
Sources
- 26 U.S.C. § 170 — Charitable contributions and gifts (Legal Information Institute)
- 26 U.S.C. § 68 — Overall limitation on itemized deductions (Legal Information Institute)
- 26 U.S.C. § 4940 — Excise tax on net investment income (Legal Information Institute)
- 26 U.S.C. § 4942 — Taxes on failure to distribute income (Legal Information Institute)
- Internal Revenue Service — Publication 526, Charitable Contributions
- Internal Revenue Service — Publication 590-B, Distributions from Individual Retirement Arrangements
- Internal Revenue Service — Notice 2025-67, 2026 Limitations Adjusted as Provided in Section 415(d), etc.
- Internal Revenue Service — Tax Inflation Adjustments for Tax Year 2026
- Internal Revenue Service — Net Investment Income Tax
- Illinois Department of Revenue — Income Tax Rates
This article is part of our Tax Planning Guide, which collects our writing on the topic with answers to common questions.
Market Compass · weekly
Get the Compass by email
One concise recap of the week’s market-moving events and what to watch next, written by our CIO at the end of each market week.
Managing Partner and Founder; advises families, business owners and family offices through the VistaWealth Office™ and leads Vistamark’s private markets research. More about Sean →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.