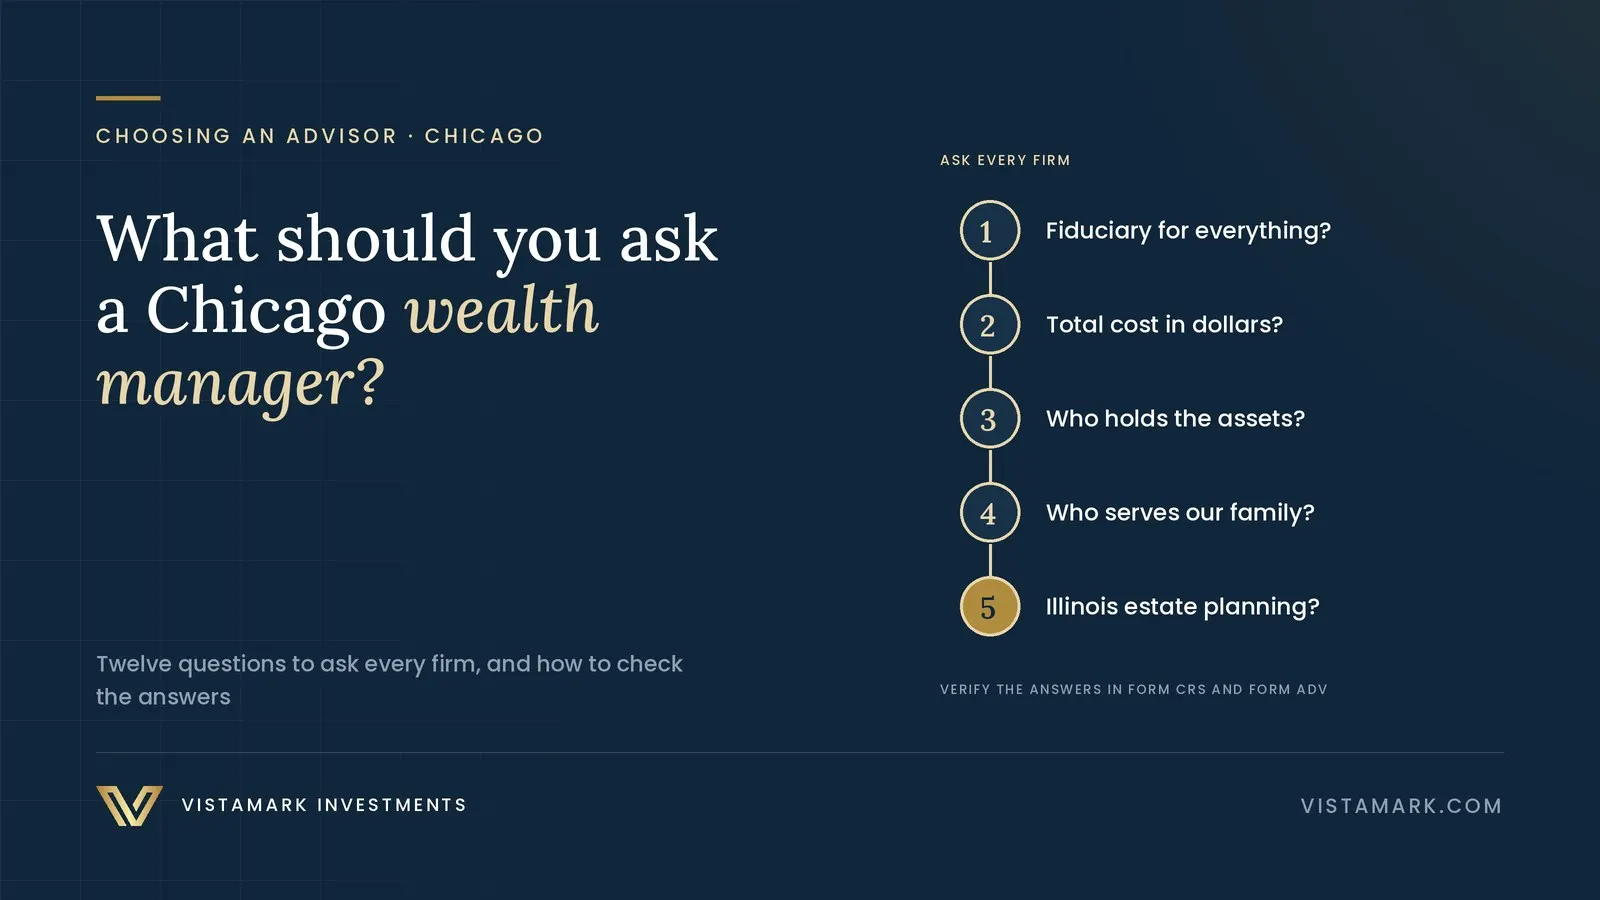
The short answer. Ask every Chicago wealth manager the same twelve questions, in writing, and compare the answers side by side. The ones that matter most: Are you a fiduciary for everything you do for us? What will we pay, in dollars, all-in? Who holds our assets? Who will actually serve our family, and what happens if that person leaves? How will you coordinate our taxes and our Illinois estate plan with our CPA and attorney? Then check each answer against the firm’s own regulatory filings, which are free on Investor.gov.
Which questions matter most?
The questions that matter most cover fiduciary duty, total cost in dollars, how the firm is paid, who holds your assets, who will serve your family and what happens if that person leaves. The table lists twelve questions, what a strong answer sounds like and the warning signs.
| Question | A strong answer | A warning sign |
|---|---|---|
| 1. Are you a fiduciary for every service you provide us? | Yes, in writing, for all accounts and advice | “For advisory accounts,” with commissions elsewhere |
| 2. What will we pay each year, in dollars? | One figure covering the advisory fee, fund expenses and any planning or reporting fees | Only a percentage, or costs that appear later |
| 3. How are you paid, and by whom? | Only by clients | Commissions, revenue sharing or referral fees from product providers |
| 4. Who holds our assets? | An independent qualified custodian that sends statements directly to you | The adviser holds assets itself without independent checks |
| 5. Who will serve our family day to day? | Named senior people you meet before signing | A team you meet only after you move assets |
| 6. How many families does each senior advisor serve? | A number small enough for real attention | No clear answer |
| 7. What happens if our advisor retires or the firm is sold? | A written succession plan and ownership that is stable | “We haven’t had to think about that” |
| 8. How do you coordinate with our CPA and estate attorney? | Regular joint meetings and one shared plan | Investment management only, coordination left to you |
| 9. How do you plan for Illinois taxes? | Specific answers on the $4 million Illinois estate tax and after-tax investing | Generic federal-only planning |
| 10. How do you invest, and how will we measure success? | A written investment policy and benchmarks agreed in advance | Performance claims without context |
| 11. Do you use proprietary funds? | No, or full disclosure of how conflicts are handled | House funds recommended by default |
| 12. What is your disciplinary history? | None, or a clear explanation that matches the filings | An answer that differs from the public record |
Why ask about fiduciary duty first?
A registered investment adviser owes clients a fiduciary duty, but many firms and individuals also act as broker-dealers or insurance agents, and those roles carry different obligations and pay. Ask whether the fiduciary standard applies to everything the firm does for you, including insurance, retirement accounts and any products it recommends. The firm’s relationship summary, Form CRS, must describe its services, fees, conflicts of interest, standard of conduct and any disciplinary history, in plain English and in a standard order so you can compare firms (SEC, Investor.gov).
How should you compare what wealth managers cost?
Ask every firm to state its total annual cost for your family in dollars, using your actual balance sheet: the advisory fee, the expense ratios of any funds it uses, fees on private investments, and any separate charges for tax preparation, financial planning, bill pay or reporting. A percentage fee that looks small can become a large dollar figure on a large portfolio, and two firms with the same headline fee can differ widely once fund expenses and extra services are added. Then ask what is included for that amount. Our guide How to Choose a Chicago Wealth Advisor for $25 Million and Up walks through the comparison.
Why does it matter who holds your assets?
Most advisers do not hold client money themselves. Assets sit with a qualified custodian, such as a bank or brokerage firm, which sends account statements directly to you (SEC, Investor.gov). Compare those custodian statements with the adviser’s reports. If the adviser can withdraw funds or move money between accounts, ask what controls and audits apply.
What should Chicago families ask that others might not?
Chicago-area families should also ask how a firm plans for the Illinois estate tax, which applies to estates above $4 million, and how it handles business sales, executive stock compensation, winters spent in another state and family office services.
- The Illinois estate tax. Illinois taxes estates above $4 million, far below the $15 million federal exemption, and the Illinois exemption cannot be passed to a surviving spouse. Ask how the firm plans for it with your attorney.
- Business sales. Many Chicago-area fortunes come from private companies. Ask how the firm prepares owners before a sale and invests the proceeds after one.
- Executive compensation. Ask how the firm handles stock options, restricted stock and concentrated positions in a Chicago-headquartered employer.
- Moving out of state. If you spend winters in Arizona or Florida, ask how the firm advises on domicile, income tax and the Illinois estate tax that can still apply to Illinois property.
- Family office services. Ask whether you need a full family office or a wealth manager that coordinates your advisors; our article Family Office vs. Wealth Manager compares them.
How do you check a firm’s answers?
Check every answer against the firm’s Form CRS and Form ADV, which are free on Investor.gov, ask for a sample client report, and meet the person who would actually manage your relationship before deciding.
- Search the firm and each advisor on Investor.gov’s “Check Out Your Investment Professional” tool, and read the firm’s Form CRS.
- Read Form ADV Part 2A, the firm brochure, for fees, conflicts, custody and disciplinary history; compare it with what you were told.
- Ask for a sample client report and a sample investment policy statement.
- Ask to speak with the person who would actually manage your relationship, not only the person presenting.
- Put the answers to all twelve questions side by side before deciding.
If your current advisor is part of a larger firm, also ask about its succession plan; our article Passing the Baton explains why it matters.
How does Vistamark answer these questions?
The VistaWealth Office is the private wealth practice of Vistamark, an independent, employee- and partner-owned firm based in Chicago and Hinsdale. Vistamark is a registered investment adviser and a fiduciary to every client. It is not a broker-dealer, does not sell proprietary products, has no minimum, and charges one advisory fee, asset-based or flat, described on Our fees. It does not take custody of client assets, which are held at an independent custodian; the firm prefers Charles Schwab and can work with other custodians. The VistaWealth Office coordinates each family’s plan with its CPA and estate attorney. Our Form CRS and Form ADV are linked from our Disclosures page, so you can check every answer above.
Sources
Founder and CIO of Vistamark; as CIO of Fiducient Advisors, oversaw investment strategy for more than $260 billion in client assets. More about Matthew →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.