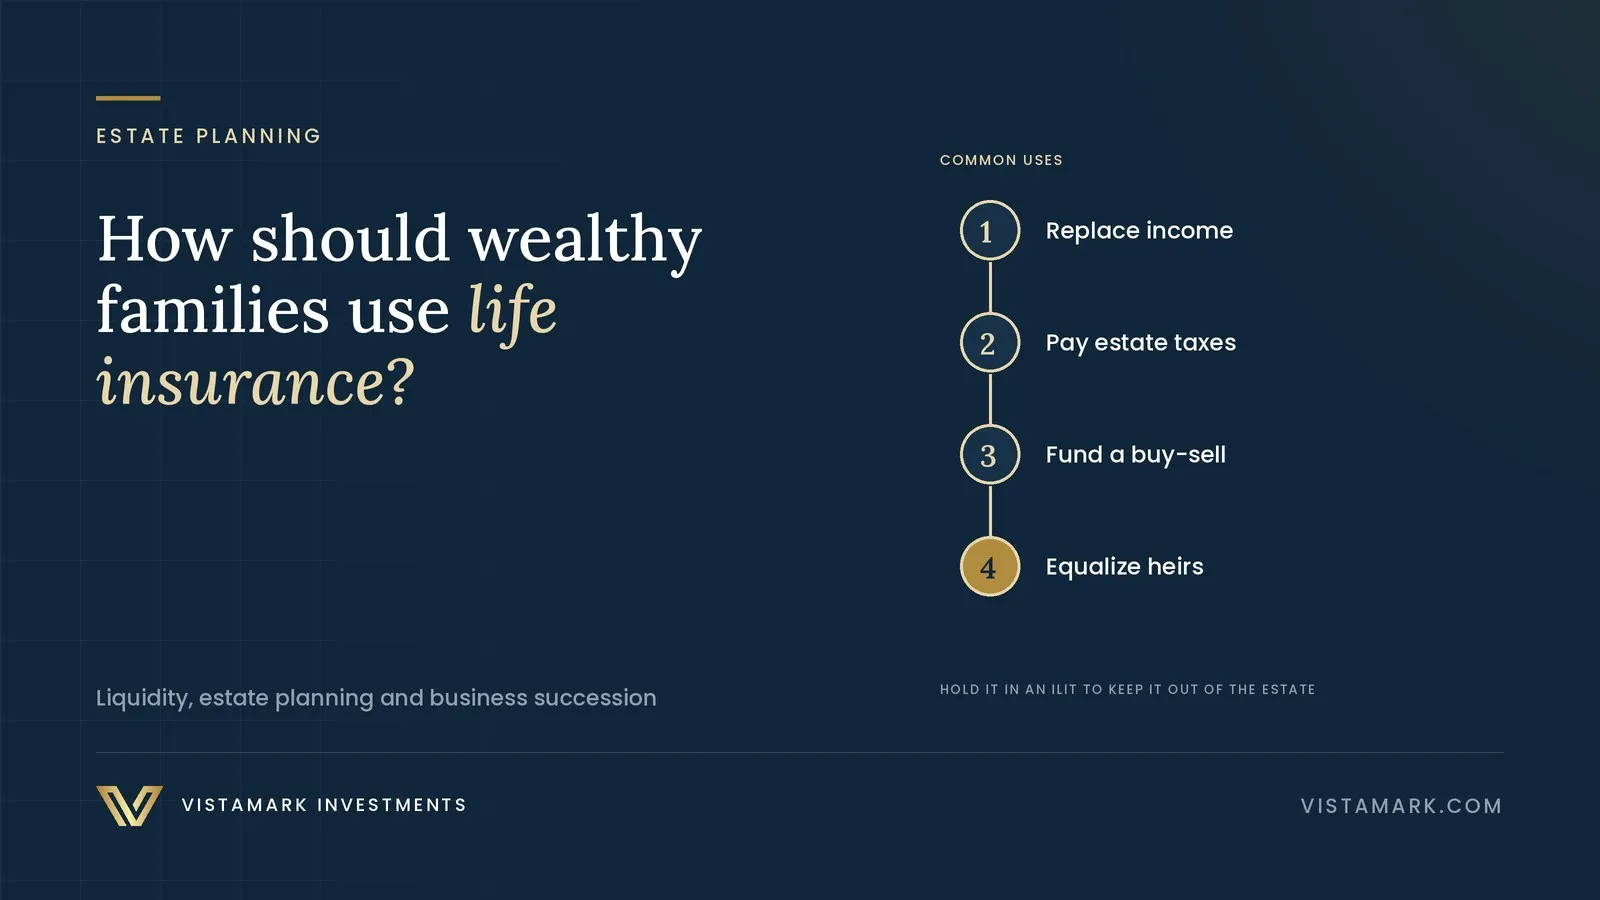
The short answer. Wealthy families use life insurance mainly to create cash at the moment it is needed: to pay estate taxes without selling a business, real estate or private investments, to fund a buy-sell agreement, and to give children who do not inherit the business a fair share. In Illinois, which taxes estates above $4 million, a family can need that cash even when it owes no federal estate tax under the $15 million exemption. Large policies are usually best owned by an irrevocable life insurance trust (ILIT), which keeps the death benefit out of the taxable estate.
Why would a wealthy family need life insurance?
- Estate tax liquidity. Estate taxes are generally due nine months after death, and estates heavy in a business, real estate or private funds may have little cash. Insurance pays the bill without a forced sale.
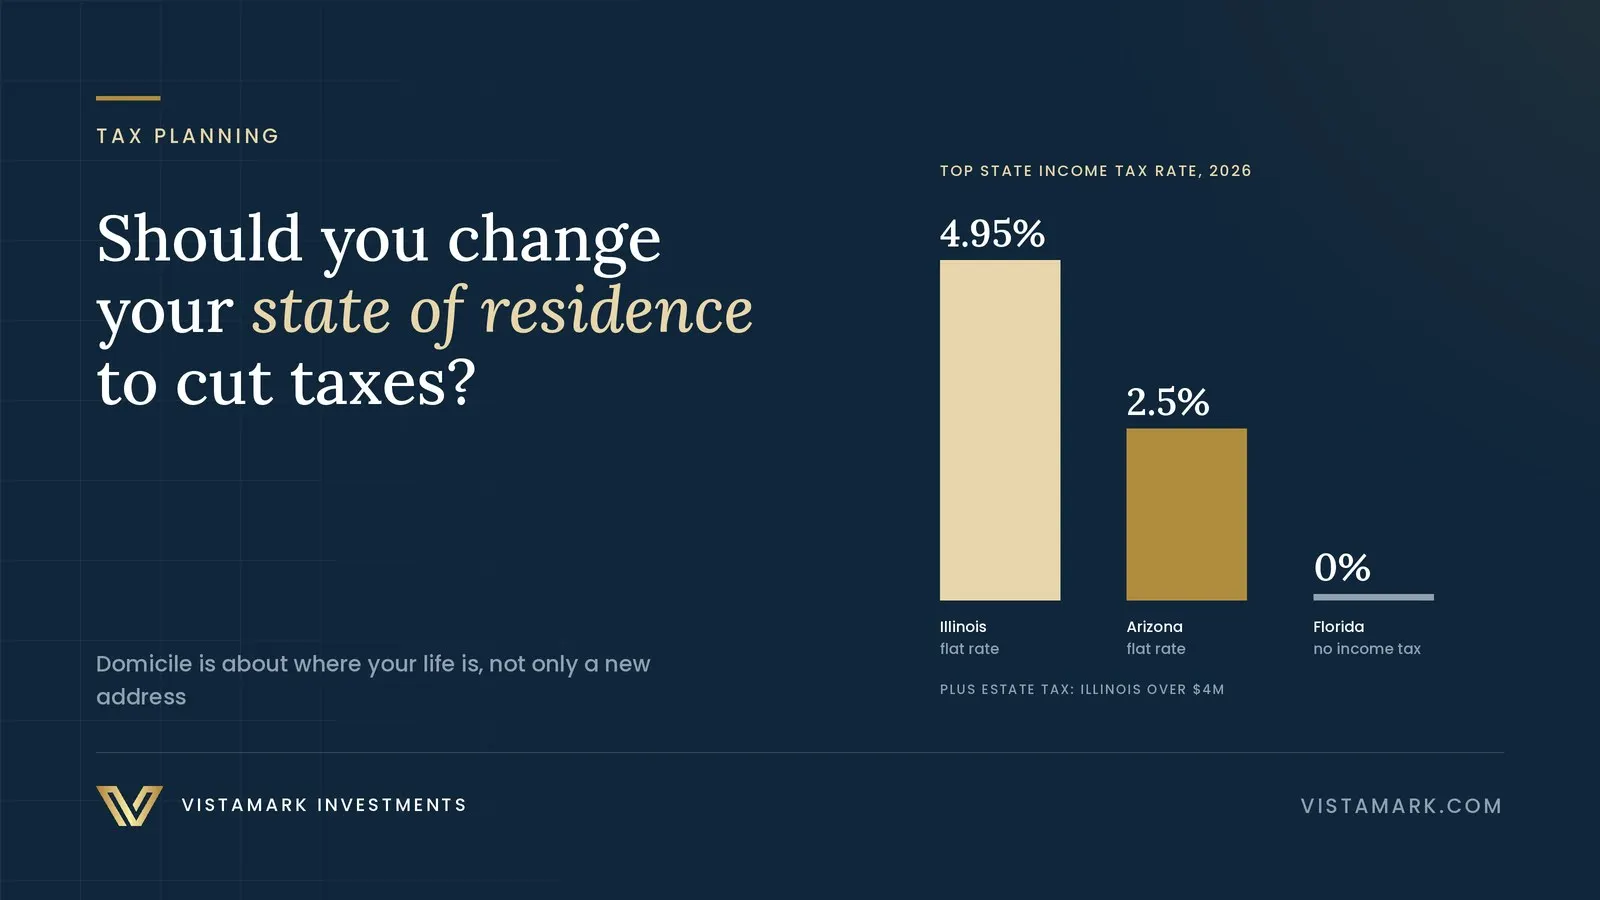
- Illinois estate tax. Illinois taxes estates above $4 million, and its exemption cannot be passed to a surviving spouse (Illinois Attorney General). The federal exemption is $15 million per person in 2026 (IRS). Many Chicago-area families therefore face a state bill with no federal one.
- Business succession. Insurance can fund a buy-sell agreement, so surviving owners can buy out a deceased owner’s family at an agreed price.
- Equalizing inheritances. When one child inherits the family business or a property, insurance can provide a comparable inheritance for the others.
- Income replacement for families who still depend on earned income.
- Philanthropy, by naming a charity or the family foundation as beneficiary.
How much life insurance does a wealthy family need?
Start with the problem, not the product. The insurance need is the gap between the cash the estate will owe and the cash it will have:
Insurance need = estimated estate taxes + buy-sell and equalization amounts + other obligations − liquid assets available at death.
For example, suppose a married Chicago couple’s estate attorney estimates an Illinois estate tax of $900,000 at the second death, the couple wants $2 million to equalize an inheritance for a child who will not run the family business, and the estate is expected to hold $500,000 in cash and marketable securities beyond what the surviving family needs. The gap is $2.4 million, a reasonable starting point for coverage. The figures are illustrative; your own attorney’s tax estimate sets the real number, and it should be updated as assets grow.
What types of policies are used?
| Type | What it is | Typical use |
|---|---|---|
| Term | Coverage for a set period, no cash value | Income replacement and temporary needs; lowest cost |
| Guaranteed universal life | Permanent coverage with a guaranteed death benefit and little cash value | Estate liquidity at a predictable cost |
| Whole life | Permanent coverage with guaranteed cash value growth | Estate liquidity with a conservative savings component |
| Survivorship (second-to-die) | Insures two lives and pays at the second death | Estate taxes, which married couples usually owe at the second death |
| Private placement | Institutionally priced variable policies for very wealthy, qualified buyers | Tax-efficient growth of investments inside a policy |
Why hold life insurance in an irrevocable life insurance trust?
A policy you own on your own life, or over which you keep “incidents of ownership” such as the right to change the beneficiary, is included in your taxable estate (26 U.S.C. § 2042). A $5 million policy can therefore create part of the very tax it was bought to pay. An ILIT owns the policy instead and keeps the proceeds out of the estate. At death, the trust can lend cash to the estate or buy assets from it, so the estate can pay its taxes, and hold the rest for the family under the trust’s terms.
Two details matter. First, an existing policy transferred to an ILIT is pulled back into the estate if the insured dies within three years of the transfer (26 U.S.C. § 2035), so for new coverage the trust should usually buy the policy itself. Second, premiums are paid by gifts to the trust; with properly drafted withdrawal rights, often called Crummey powers, those gifts can qualify for the annual gift tax exclusion of $19,000 per beneficiary in 2026 (IRS). Illinois has no gift tax.
Does every wealthy family need an ILIT?
No. A family whose estate, including the death benefit, will stay below the Illinois threshold, or whose policy is small or temporary, may be well served by owning it personally or through a revocable trust. An ILIT adds legal cost, a trustee and annual administration. It earns its keep when the death benefit would otherwise push the estate over $4 million in Illinois, or add to a federal tax for estates above $15 million per person.
What are common life insurance mistakes?
- Buying permanent insurance mainly as an investment without comparing it with simpler alternatives.
- Owning large policies personally instead of through an ILIT.
- Never reviewing existing policies, which can lapse if they were funded on optimistic interest or dividend assumptions.
- Planning only for the federal estate tax and overlooking Illinois.
- Buying from an agent paid by commission without an independent review of the need and the pricing.
Where should a family start?
- Gather every existing policy, and ask each insurer for an in-force illustration showing how the policy performs under current assumptions.
- Ask your estate attorney for an estimate of Illinois and federal estate taxes under your current plan.
- Compare the estate’s cash needs with its liquid assets and existing coverage.
- Decide who should own any new policy, usually an ILIT, before applying.
- Review the plan every few years and after major events such as a business sale.
Where does Vistamark fit?
The VistaWealth Office is the private wealth practice of Vistamark, an independent, employee- and partner-owned firm based in Chicago and Hinsdale. It coordinates insurance reviews with each family’s estate attorney and insurance specialists, measures the liquidity need against the family’s full balance sheet, and keeps the policies, trusts and investment plan aligned as assets grow. Our article Essential Estate Tax Strategies for Married Couples covers the trusts that work alongside insurance. This article is general information, not legal, tax or insurance advice.
Sources
- Illinois Attorney General — Important Notice Regarding Illinois Estate Tax and Fact Sheet
- Internal Revenue Service — What’s New, Estate and Gift Tax
- Internal Revenue Service — Frequently Asked Questions on Gift Taxes
- Legal Information Institute — 26 U.S.C. § 2042, Proceeds of Life Insurance
- Legal Information Institute — 26 U.S.C. § 2035, Transfers Within Three Years of Death
This article is part of our Estate Planning Guide, which collects our writing on the topic with answers to common questions.
Managing Partner, VistaWealth Office™ — integrated wealth planning for executives, business owners, family offices and charities. More about William →
This article is for informational and educational purposes only and does not constitute investment, legal, tax or accounting advice, or an offer or solicitation to buy or sell any security. Views are those of the author as of the publication date and are subject to change. Vistamark Investments is an SEC-registered investment adviser; see our disclosures.