
Topic
Retirement Plan Sponsors
Fiduciary guidance for 401(k), 403(b), defined benefit and cash balance plan sponsors and committees.
How Vistamark helps: Retirement Plan Sponsors →
Members of a retirement plan committee are ERISA fiduciaries, and the duty is personal: act solely in the interest of participants, follow a prudent process, and keep plan costs reasonable. Most claims against plan sponsors focus on process rather than results: fees that were never benchmarked, decisions that were never documented, and an investment lineup nobody reviewed against the plan’s investment policy statement.
These guides are written for the people who sit on 401(k), 403(b), defined benefit and cash balance plan committees: HR and finance leaders, executives, and the trustees of plans sponsored by nonprofits and professional firms. Each one turns a fiduciary duty into the documents and meeting habits that demonstrate it.
Start here
- A 401(k) committee member’s fiduciary duties
- Writing a 401(k) investment policy statement
- Five practices that help prevent fiduciary lawsuits
- Managed accounts in defined contribution plans
- Traditional vs. Roth 401(k) contributions
- How cash balance plans work
- Asset-liability management for defined benefit plans
- Collective investment trusts in 403(b) plans
Reviewing your plan consultant? Our free RFP template includes an optional section for ERISA plan sponsors, and our retirement plan practice explains how we work with committees.
 Choosing an Investment Advisor
OCIO vs. Investment Consultant vs. In-House CIO
OCIO vs. investment consultant vs. in-house CIO: who decides, who carries the liability, what each costs, and where an…
 Foundations & Endowments
What Should a New Investment Committee Chair Do in the First 90 Days?
A new investment committee chair’s first 90 days: read the governing documents, check positioning against policy, meet…
 Foundations & Endowments
When Should an Investment Committee Fire an Underperforming Manager?
Fire an investment manager when the reason you hired it no longer holds, not just after weak returns. How committees…
 Retirement Plan Sponsors
The Case for Managed Accounts in Defined Contribution Plans
Large 401(k) and DC plans can get managed accounts for under 0.20%, close to target-date fund costs, with advice…
 Retirement Plan Sponsors
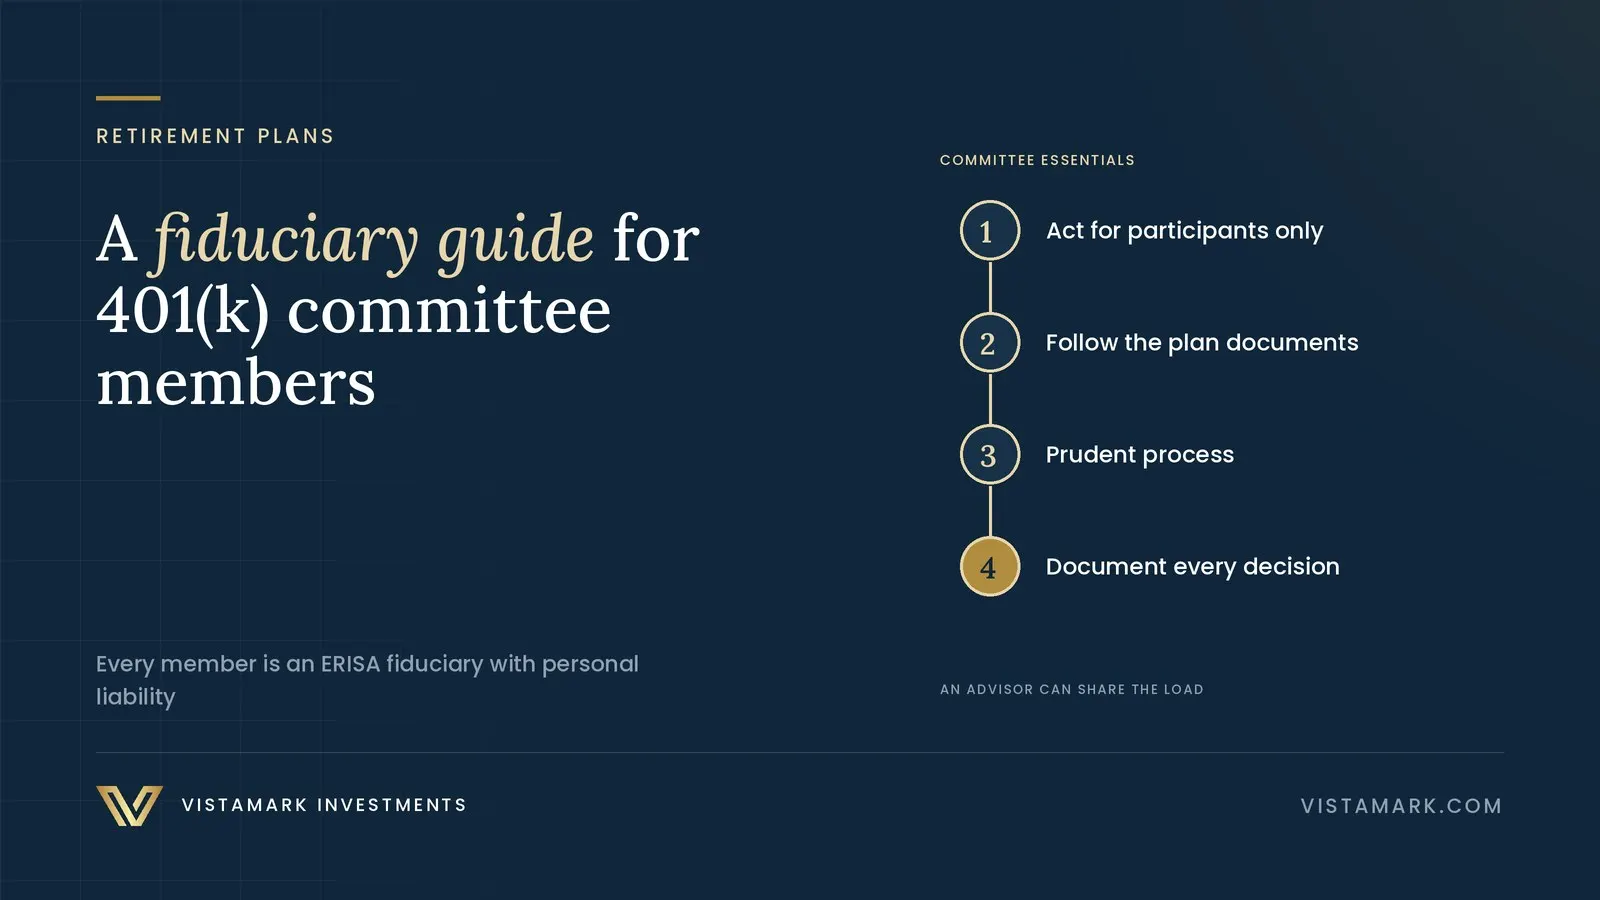
Navigating Your Fiduciary Compass: A Guide for 401(k) Investment Committee Members
401(k) committee members are ERISA fiduciaries with personal liability. The core duties, committee best practices and…
 Retirement Plan Sponsors
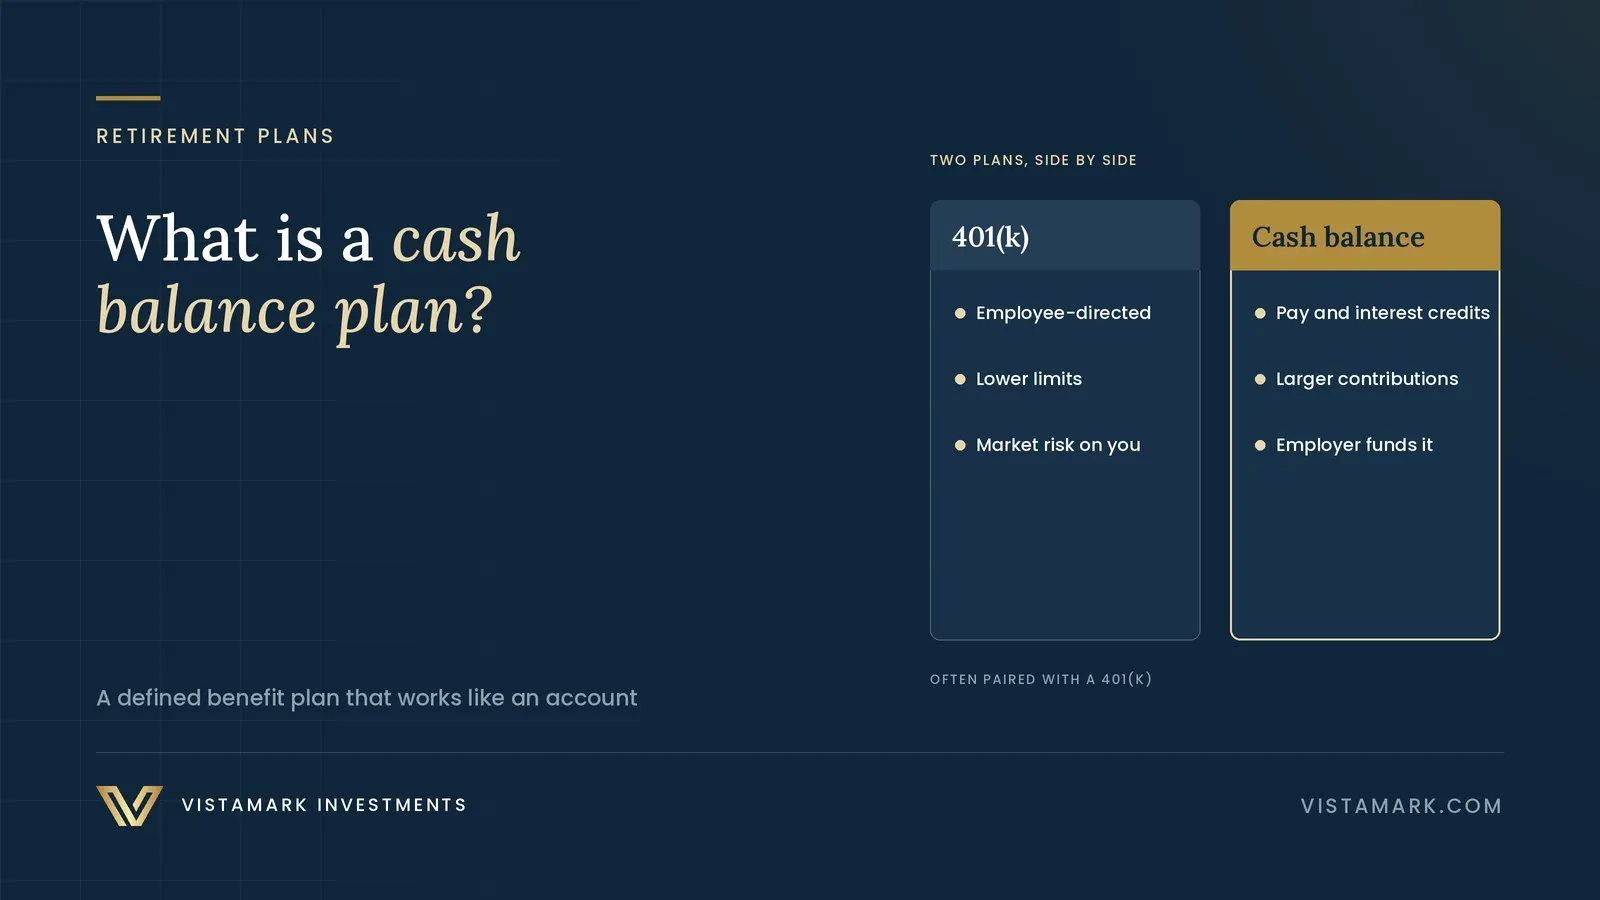
Cash Balance Plans: The Hybrid Solution Powering Retirement and Tax Savings
Cash balance plans let high-earning business owners make tax-deductible contributions that can top $200,000 a year. How…
- Crafting Your 401(k) Investment Policy Statement: Your Roadmap to Retirement Success
- Savings vs. Debt: How to Master Your Money Priorities
- The Vista of Insight and the Mark of Excellence: Why We Founded Vistamark Investments
- Shield Your 401(k) Plan: 5 Essential Strategies to Prevent Fiduciary Lawsuits
- Navigating the Future: Why Asset Liability Management is Key for Corporate Defined Benefit Pension Plans
- Strategic Considerations for Implementing a Roth 401(k) Option
- Traditional vs. Roth 401(k): Your Ultimate Retirement Planning Guide
- The 403(b) Revolution is Coming: What Fiduciaries Must Know About CITs
- Hedge Funds Through 2025: Evolution, Growth, and Market Dynamics – A Deep Dive